
Two businesses in the same industry, with near identical revenue and near identical EBITDA, can sell for very different prices. One might go for three times annual profit. The other goes for six. Owners are often surprised the gap can be that wide when the financials look so similar on paper.
The explanation is rarely hidden in the numbers a buyer already has. It sits in the numbers they do not have yet, the ones covering the twelve to twenty four months after settlement. A buyer is not really paying for what the business earned last year. They are paying for what they believe it will earn once they own it, discounted for the risk that belief turns out to be wrong.
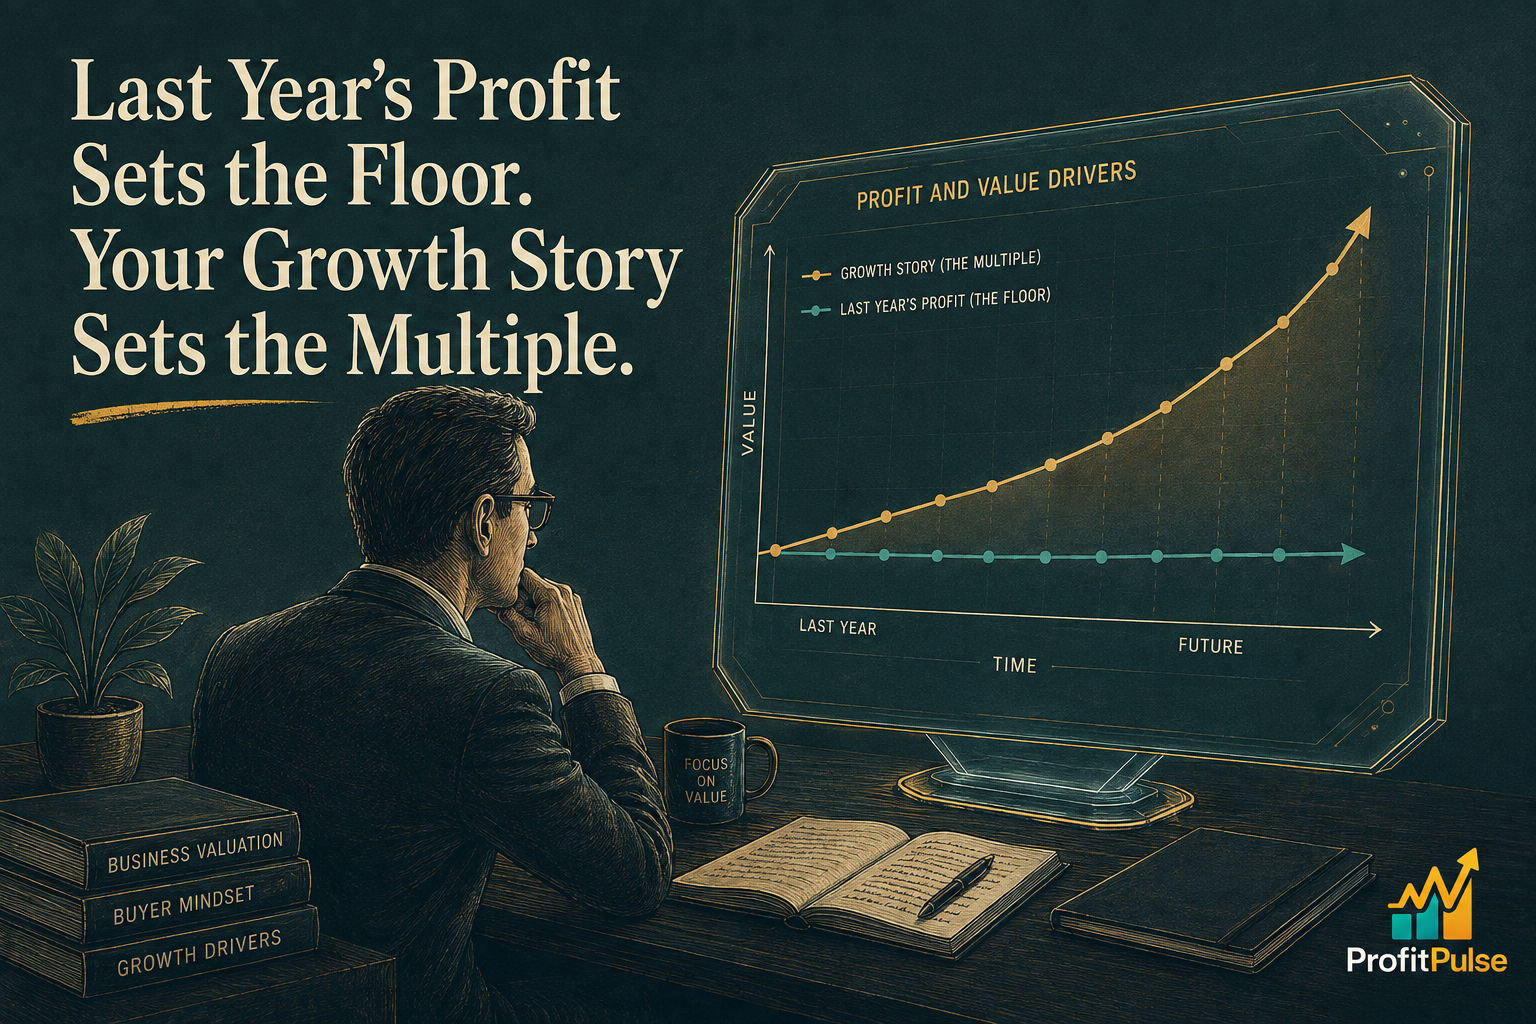
That is what a multiple actually prices. Last year’s profit sets the floor a valuation starts from. The credibility of the growth story sitting on top of it decides where in the multiple range the business actually lands.
Trailing profit sets the floor, not the price
Valuers and buyers both start in the same place, applying an industry appropriate multiple to a normalised profit figure. For businesses of a similar size in the same sector, that range might run from three to four times profit at the low end through to five or six times at the high end. The starting multiple is set by the market. Where a specific business lands inside that range is set by everything the trailing profit figure cannot show on its own, which is exactly the gap an indicative business valuation is built to close before a business goes anywhere near a buyer.
This is also why two owners comparing notes over coffee can walk away confused. One hears that a business like theirs sold for six times profit, assumes that figure applies to them, and lists at a price the market never validates. The multiple a buyer actually pays is specific to that business, not to the industry average, and the growth story is usually the single biggest reason two seemingly comparable businesses land in different parts of the range.
Why “we are growing” does not move a buyer
Every owner going to market says the business is growing. Buyers have heard that from every vendor they have ever sat across from, which is why the phrase carries almost no weight on its own. What actually moves a buyer is evidence they can check independently, not a description they have to take on faith. That means the percentage of revenue that is contracted or recurring rather than one off, retention and renewal figures tracked over several years rather than one good quarter, and a documented pipeline with a real conversion history behind it rather than a list of names an owner feels confident about. It also means whether the forecasts issued in the last two or three years were actually hit, or quietly revised down each time reality caught up with them.
A growth story that runs through one relationship does not transfer
The next question a buyer asks is who the growth actually depends on. If the pipeline is full because the owner has spent fifteen years building relationships with the right people, that pipeline is worth less to a buyer than it looks, because there is no guarantee it survives a change of ownership. This is the same owner dependence pattern that shows up across almost every sale ProfitPulse has been involved in preparing for. The fix is not to work less on relationships. It is to make sure more than one person in the business owns them, that they are recorded in a system rather than a head, and that a buyer can see the sales function would keep functioning with a different name on the email signature.
The preparation happens years before the listing, not during it
None of this is built in the weeks before a business goes to market. A credible growth story is the output of two or three years of consistent forecasting discipline, where the business sets a number, tracks against it, and can show a buyer the pattern of hitting it. Owners who start this work early are not just protecting their sale price, they are running a better business in the meantime, because the same forecasting discipline that convinces a buyer is what keeps decisions grounded in the years before a sale is even on the table. It is also the groundwork behind a proper information memorandum, which lives or dies on whether the growth numbers inside it are backed by a track record rather than optimism.
The businesses that sell well are rarely the ones that scrambled to build a growth story in the final year. They are the ones where an outside eye was brought in early enough to test the forecast, tighten the evidence, and make sure the story a buyer eventually hears is one the numbers can actually support, well before a listing agent or a buyer ever asks the first question.
Frequently asked questions
Why do two businesses with the same profit sell for different prices?
The starting multiple for a business is set by its industry and size, using trailing profit as the base. Where a specific business lands inside that range depends on how believable its growth story is to a buyer, not on the profit figure alone. Two businesses with identical numbers can land at very different points in the same range for that reason. A business valuation looks at both the base figure and the drivers sitting above it.
What actually makes a growth story credible to a buyer?
Buyers respond to evidence they can check, not to confidence. That includes the proportion of revenue that is contracted or recurring, renewal and retention data tracked over several years, a documented pipeline with a real conversion history, and a track record of forecasts that were actually hit rather than quietly revised down. Verbal assurance about future growth carries very little weight without that evidence behind it.
How far ahead should an Australian SME start preparing to sell?
Most of the evidence a buyer wants to see, consistent forecasting, documented pipeline, retention data over multiple years, cannot be produced quickly. Two to three years ahead of a planned sale gives enough time to build that track record properly. An exit readiness diagnostic is a useful way to see where the gaps sit well before a business goes anywhere near the market.
Does recurring revenue increase the price a business sells for?
Generally yes. Recurring or contracted revenue is easier for a buyer to underwrite because it reduces the uncertainty around what happens after settlement. A business with a high proportion of one off or project revenue asks a buyer to take more on faith about the year ahead, which typically shows up as a more conservative multiple rather than a lower profit figure.
How much does owner dependence affect a business’s sale price?
It can be significant, particularly where the growth pipeline runs through the owner’s personal relationships rather than the business itself. Buyers discount for the risk that pipeline does not survive a change of ownership. Spreading key relationships across more than one person and recording them in a system rather than a head is one of the more common gaps we see in exit readiness work.
What should be included in an information memorandum about growth?
A credible growth section shows the evidence behind the numbers, not just the numbers themselves. That means contracted revenue, historical conversion rates on the pipeline, and a track record of forecasts that were actually met. Buyers read growth claims in an information memorandum with scepticism until the supporting evidence is visible alongside them.
Leave a Reply