
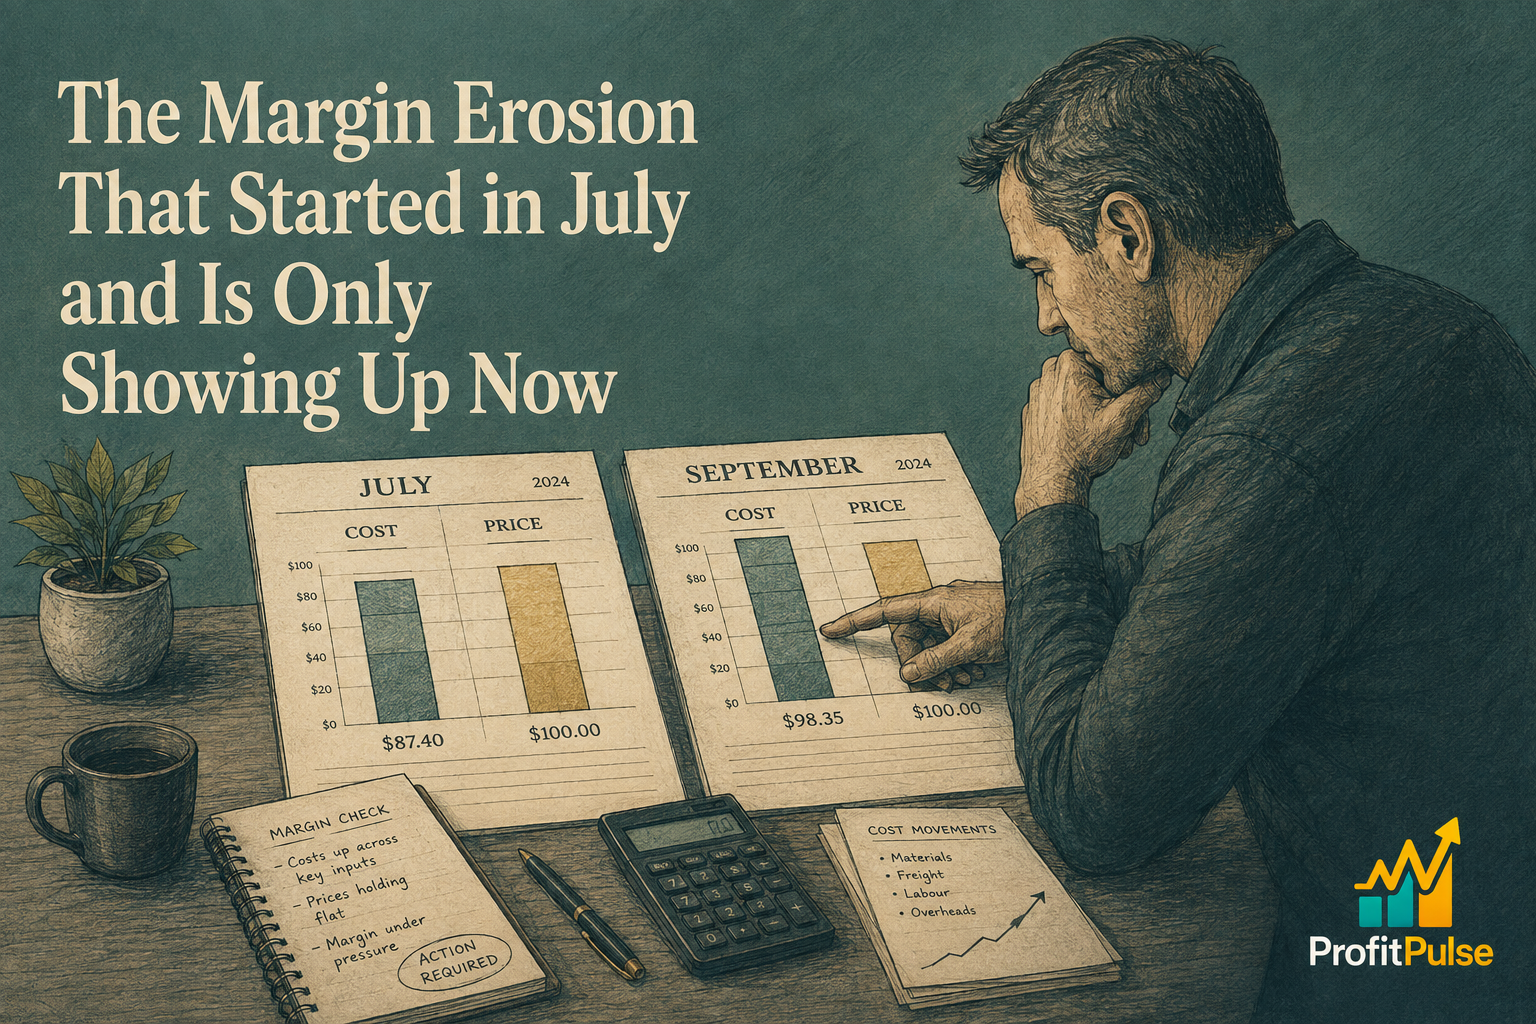
The September numbers land and revenue looks healthy, maybe even better than winter. But the margin underneath it is a notch thinner than it should be, and nothing this month explains why. No bad debt, no write-off, no obvious mistake. Just a P&L that quietly delivers less than it used to for the same amount of work.
The usual explanation is two months old. On 1 July, award wages stepped up, insurance renewals landed, key suppliers reset their price lists, and any lease on a CPI or fixed-percentage review adjusted from the new financial year. None of that hit straight away, because the jobs quoted in May and June were still being delivered through July and into August at the old numbers. Most businesses don’t compare a July cost base against a July price list. They compare this month’s revenue to this month’s costs, see a result that’s roughly in the usual range, and move on.
By September, the last of the old-priced work has cleared the pipeline. What’s left is the new cost base sitting against pricing that hasn’t moved. This is usually the first month that shows the true picture, and it tends to arrive quietly enough that owners assume it’s just a slow patch rather than the actual, ongoing shape of the business.
What Actually Reset on 1 July
None of the individual increases are unusual. Award and minimum wage movements flow through payroll and the on-costs that sit on top of it, and for any business carrying a meaningful share of its team on award rates, that’s not a marginal shift. Insurance premiums, public liability, professional indemnity, workers compensation, tend to renew mid-year and rarely move down. Suppliers frequently use 1 July as their own reset point for price lists, particularly where their own input costs have moved. Landlords on CPI-linked or fixed-percentage reviews adjust rent from the start of the new financial year. Businesses have absorbed each of these before. What’s different is that they land inside the same six-week window, and the combined effect rarely gets modelled as one number.
Why the Damage Takes Two Months to Surface
Work already quoted and in progress in June and July gets delivered at the old price, so the wage and supplier increases sitting underneath it eat into margin without anyone noticing at the job level. Job costing usually lags behind the pay run by weeks, sometimes longer, and a business running on thin admin capacity often doesn’t reconcile the two until the quarter is well underway. Most owners are also reading this month’s result against last month’s, or against the same month a year ago, not against a budget that has been rebuilt around the new cost base. Without that rebuilt reference point, a genuinely tighter margin reads as ordinary month-to-month noise rather than the structural shift it actually is, and it can sit there unaddressed for another quarter simply because nothing in the reporting flags it as different from the usual seasonal wobble.
There’s also a timing effect that catches businesses with longer sales or project cycles particularly hard. A construction business or a professional services firm carrying jobs quoted three or four months earlier can still be delivering against June pricing well into September, which means the true cost base hasn’t fully worked its way through the order book yet. For these businesses the erosion isn’t a one-off correction, it’s a slow bleed that keeps showing up for another quarter or two after the initial cost increases land, and it compounds every week the old pricing stays live.
The Pricing Conversation Most Businesses Deferred
Plenty of owners intend to revisit pricing around EOFY, then the conversation with customers feels awkward in the moment and gets pushed to the next quote cycle, the next contract renewal, the next time it comes up naturally. That’s a reasonable instinct, most people would rather avoid an uncomfortable conversation than force it. It also means the old prices carry the new cost base for months longer than planned, which is exactly the gap showing up in September. This is the point where a Cost & Margin Deep Dive earns its keep, because it separates which cost increases are genuinely fixed from which ones can still be negotiated back down with suppliers, and which prices need to move regardless of how the conversation feels in the moment.
None of this is a September problem. It’s a July decision, or a July non-decision, finally visible in the numbers. A margin review doesn’t need to wait for the next natural pricing season to come around, and the gap between your cost base and your current pricing doesn’t close itself by waiting either, whether the business is based on the Gold Coast or anywhere else along the East Coast. It’s worth having the conversation before it compounds through another quarter, whether that means unpicking exactly where the increases landed hardest or working out what a defensible price move looks like for the customer base you actually have. If you would rather talk it through than dig through the spreadsheet alone, you can book a discovery call and bring the numbers with you.
Frequently asked questions
Why did my profit margin drop even though revenue stayed about the same?
The usual cause is a cost base that reset before pricing did. Wage increases, insurance renewals, supplier price rises and rent reviews often land together around 1 July, but the effect only shows up once work quoted at the old prices has cleared the pipeline. A Cost & Margin Deep Dive usually finds it within a single review.
How do I know if my current prices still cover my actual costs?
Rebuild your cost base from scratch rather than adjusting last year’s numbers, then compare it line by line against what you’re currently charging. Most owners are surprised by how much has moved since the last pricing review, particularly on the supplier and insurance side.
When is the right time for an Australian SME to review pricing after a cost increase?
As soon as the new cost base is confirmed, rather than waiting for the next natural renewal cycle. Every month a price stays fixed against a higher cost base is margin that doesn’t come back. It doesn’t need to be a full reset, a targeted adjustment on the affected lines is often enough.
What is the fastest way to find where margin is leaking in my business?
Compare this year’s cost base to last year’s, line by line, rather than looking at the P&L in isolation. Wages, insurance, supplier terms and rent are the four places increases most often hide. This is the exact gap a Cost & Margin Deep Dive is built to surface quickly.
Should wage and super increases automatically flow through into my pricing?
Not automatically, but they should be modelled every time they land. Some increases can be absorbed through efficiency, others genuinely need to be priced in. The mistake isn’t absorbing a cost rise, it’s absorbing it without deciding to.
How often should I be reviewing supplier pricing and terms?
At least once a year, ideally timed to when your major suppliers tend to reset their own price lists. Many businesses only revisit supplier terms when a price rise arrives unannounced, which is the more expensive way to find out.
Can a fractional CFO help fix a margin that’s quietly shrinking?
Yes. A fractional CFO rebuilds the cost base against current pricing, flags exactly where the gap opened, and helps run the pricing conversation with the numbers to back it. It’s usually faster to resolve with a second, financially literate set of eyes on it.
Leave a Reply