
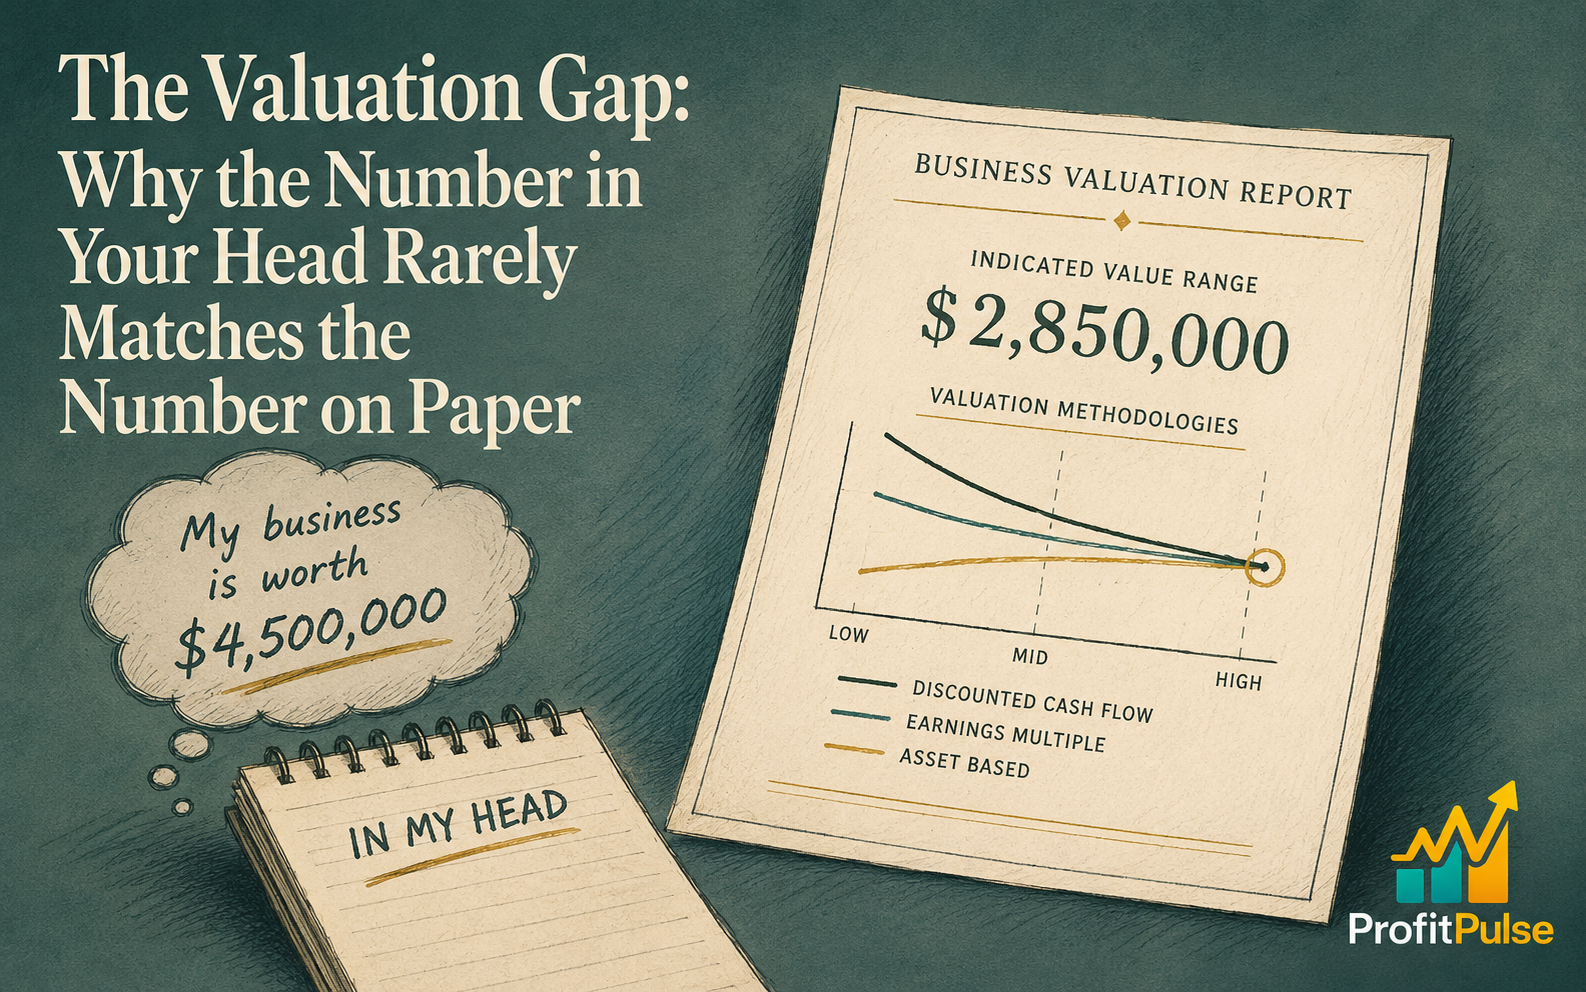
Ask most owner-led business owners what their business is worth and a number comes back quickly, usually without much hesitation. Ask where that number came from and the answer is a lot less precise: a rough multiple mentioned by a peer, a figure that feels proportionate to the years put in, or simply what the mortgage and the next chapter of life would need. It is a perfectly human way to arrive at a number. It is also rarely the number a formal valuation produces.
The gap between the two is not a failure of judgement on the owner’s part. It is what happens when a business gets valued against effort and memory instead of against cash flow, risk and comparable transactions. The trouble is not that the gap exists. It is that most owners only discover its size at the exact moment they can least afford to be surprised by it, partway through a sale process or a shareholder exit, with a timeline already running.
Where the Number in Your Head Comes From
The figure most owners carry tends to be built from three ingredients: what the business felt like it cost them to build, what a similar business down the road reportedly sold for, and a rough multiple of revenue picked up somewhere along the way. Each of those inputs makes intuitive sense on its own. None of them is how a buyer, a bank or the Australian Taxation Office actually prices a business.
Effort is a real cost, but it is not a value driver a buyer pays for. Two businesses can represent identical years of sacrifice and sell for wildly different multiples, because the buyer is pricing the earnings that continue after settlement, not the hours already spent. The peer benchmark is often just as unreliable, since sale prices reported informally rarely include the deal structure behind them, the proportion paid as an earnout, or the working capital adjustment that moved the final number well away from the headline figure. A revenue multiple, meanwhile, ignores the one thing that determines almost everything else: what proportion of that revenue actually converts to profit a new owner can rely on.
What a Formal Valuation Actually Measures
A proper valuation triangulates rather than guesses. It typically runs the business through three methodologies at once: an EBITDA multiple benchmarked against comparable transactions in the same industry and revenue band, a discounted cash flow model that prices the earnings the business is expected to generate going forward, and an asset-based view as a floor check. Where those three methods land close together, the number carries real weight. Where they diverge sharply, the divergence itself is informative, often pointing straight at customer concentration, owner dependence or a thin management layer as the reason the earnings multiple is being discounted.
This is exactly the exercise behind an indicative business valuation, and it is worth treating as a diagnostic tool rather than a one-off number for a data room. The output is not just a figure. It is a ranked list of what is adding value and what is quietly subtracting from it, which is considerably more useful to an owner eighteen months from a decision than a single dollar figure ever is. Owners who want to understand the mechanics behind the three methodologies before commissioning one can start with the business valuation guide, which walks through how each approach is built and why they can produce different answers on the same set of financials.
Why the Gap Matters Long Before You List
The owners who handle this best are not the ones with the highest valuation. They are the ones who found out what the real number was early enough to do something about the gap. A valuation commissioned two years out from a sale is a planning document. The same exercise commissioned two months out, once a buyer or a family transition has already forced the question, is closer to an autopsy. The business itself has not changed between those two moments, but the owner’s options have shrunk considerably.
Closing a valuation gap is rarely about one dramatic change. It is usually a combination of reducing customer concentration, formalising the systems that currently live in the owner’s head, and building two or three years of clean, consistent earnings a buyer can underwrite with confidence. None of that happens in the run-up to a sale. It happens in the ordinary, unglamorous work covered in a proper exit readiness review, well before a business goes anywhere near a data room.
The number in your head is not wrong because you are bad at maths. It is incomplete because it was never built the way a buyer, a bank or a court actually prices a business. Finding out where the real number sits, and more importantly why, is the difference between planning an exit and reacting to one. That conversation is worth having well before a decision forces it, and it starts with an honest look at the business as it stands today, not the business you remember building. If that is a conversation worth starting, book a discovery call and bring the number in your head along with you.
Frequently asked questions
Why does a business valuation often come in lower than what the owner expected?
Owners usually anchor on effort invested, a rough revenue multiple, or a figure a peer mentioned informally, while a formal valuation prices future earnings, risk and comparable transactions instead. The gap often points to customer concentration, owner dependence or thin systems, which a buyer discounts for even when the underlying business is genuinely sound and profitable.
What are the three main methods used to value an Australian SME?
Most valuations triangulate an EBITDA multiple benchmarked against comparable transactions in the same industry, a discounted cash flow model of expected future earnings, and an asset-based floor value. When the three methods land close together the resulting figure carries more weight, and when they diverge sharply it usually signals a specific, fixable issue inside the business.
How early should a business owner get an indicative valuation before selling?
Most value gaps take twelve to twenty four months of consistent work to close, whether that is reducing customer concentration or formalising the systems currently sitting in the owner’s head. Commissioning an indicative business valuation that far out turns the number into a planning document, rather than a surprise discovered partway through a sale process.
Does a business valuation change if there is no immediate plan to sell?
Not really. The methodology stays the same whether a sale is imminent or years away, and an indicative valuation is just as useful for shareholder agreements, succession planning or simply understanding where value is being created or lost year on year. Treating it as a one-off pre-sale exercise is where most owners leave value on the table.
What causes the biggest gap between an owner’s expected price and a buyer’s offer?
Customer concentration and owner dependence are the two most common culprits, since both directly affect how confidently a buyer can underwrite future earnings without the current owner in the room. Revenue quality and the consistency of reported profit over the last two to three years also move the number considerably.
Can a business valuation help with more than just preparing for a sale?
Yes. Valuations are commonly used for shareholder disputes, partnership entry, ATO market value requirements and capital raise discussions, not only sale preparation. An exit readiness lens is worth adding alongside it whenever the resulting valuation is likely to be tested or challenged by an outside party.
Who should an SME owner talk to before commissioning a formal valuation?
A fractional CFO or advisory partner who works across valuation, cash flow and exit readiness can usually flag the obvious value gaps before a formal report is commissioned, which makes the eventual valuation more useful. Your bookkeeper or compliance accountant remains essential for the financial records underneath it, but valuation itself sits in a different, more commercial layer of advice.
Leave a Reply