
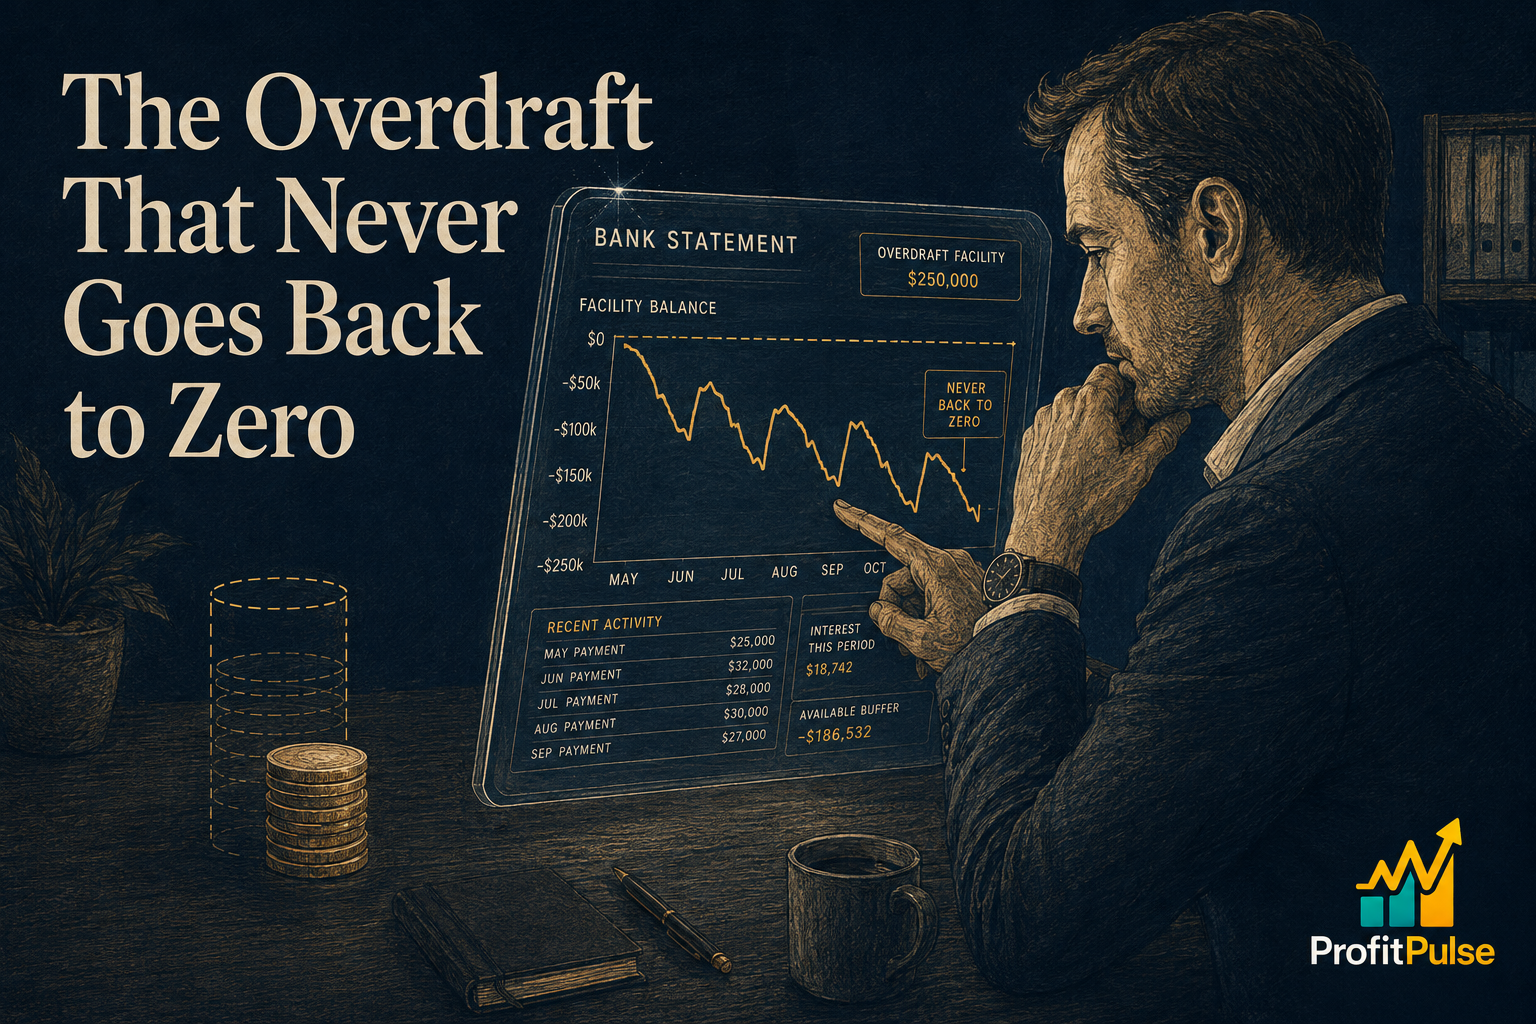
Most overdrafts start with a specific, temporary reason. A wage run that landed a few days before a large invoice cleared, a stock order that had to go out ahead of a seasonal peak, an ATO instalment that arrived in an inconvenient month. The facility gets drawn down, the immediate pressure eases, and the plan, spoken or not, is to pay it back to zero once the cash catches up.
The trouble is the next inconvenient month tends to arrive before the last one is fully repaid. The balance never quite gets back to the line it started at. Eighteen months or two trading cycles later, a facility that was approved as short-term working capital cover has quietly become a permanent fixture on the balance sheet, still priced and structured as if it were temporary.
This is not a story about a business being poorly run. It happens in growing, genuinely profitable businesses that are doing most things right. The facility simply changes purpose without anyone deciding that it should, and by the time the pattern is obvious on a statement, the business has been paying overdraft rates for what is really term capital for a year or more, without ever having the conversation that would fix it.
How a Seasonal Facility Turns Into Permanent Debt
The mechanism is rarely dramatic. A facility gets drawn down for one purpose, partly repaid, then drawn down again for the next one before the first draw has fully cleared. Watched month to month, the balance looks like it is doing its job, moving up and down with the business’s cash cycle. Watched over twelve months, a different number tells the real story, the lowest point the balance ever touches in a rolling year. That floor is the part of the facility that is never actually available for its original purpose. It has become core capital sitting inside an account that was structured, and priced, for short-term swings.
Most owners watch the limit, because the limit is what stops a payment from bouncing. Few watch the floor, because nothing forces the eye there until the bank does at the annual facility review.
What It Actually Costs to Carry Growth Capital as an Overdraft
An overdraft is priced for flexibility, not for the amount actually owed. The rate sits well above an equivalent term loan, there is no principal reduction schedule forcing the balance down over time, and the facility can be reviewed, reduced or withdrawn at the bank’s discretion rather than running to a fixed term. None of that matters much while the balance genuinely moves through zero every few months. It matters a great deal once a permanent portion has settled in, because that portion is now the most expensive, least secure form of debt on the business’s books, for something that behaves exactly like a term facility would if it were financed properly.
There is also a review risk most owners don’t see coming. Persistent utilisation near the top of a facility is one of the first things a bank notices at an annual review, and it is far more comfortable to walk into that review having already restructured the debt than to have the bank raise it first. A banking and facility review done from the business’s side, before the bank’s annual review lands, usually finds this exact pattern and puts a number on what the mismatch is costing in interest alone.
Resetting the Facility to Match How the Business Actually Uses It
The fix is rarely to eliminate the overdraft. It is to split what the facility is actually being asked to do into two instruments that are each priced for their purpose. The floor balance, the portion that never goes back to zero, gets refinanced into term debt or an asset-backed facility at a materially lower rate, with a repayment schedule that actually reduces it. What’s left is a smaller revolving facility sized to the genuine seasonal swing, the wage run before the invoice clears, the stock order before the peak, which is exactly what an overdraft is built for and priced accordingly.
Making that case to a bank takes at least twelve months of statements and a clear read on where the floor actually sits, which is easier to build from a position of strength than from inside a facility that is already stretched. Businesses that fold this into ongoing cash flow discipline tend to catch the drift within a season or two, rather than two or three years in when the floor has grown into a genuinely uncomfortable number.
None of this requires a defensive conversation with the bank. It requires an honest look at twelve months of statements to find where the real floor sits, then a facility structure that matches it rather than one inherited from whichever need happened to come up first. For business owners across Queensland, NSW and Victoria carrying this pattern into a third or fourth season, that reset is often one of the first things a fractional CFO finds when they open up the numbers, and it usually pays for itself in the interest saved alone. If that pattern sounds familiar, it’s worth booking a discovery call before the next annual facility review does it for you.
Frequently asked questions
What is the difference between a business overdraft and a term loan?
An overdraft is a revolving facility designed to cover short-term swings in cash, drawn down and repaid as the business’s cycle demands, usually priced higher because of that flexibility. A term loan is a fixed amount advanced over a set period with a defined repayment schedule, generally priced lower because the bank knows exactly when it will be repaid. The mismatch shows up when a business uses an overdraft to fund what is really permanent, term-style capital.
How can a business tell if its overdraft has become permanent debt?
Look at the lowest balance the account has touched over the past twelve months, not the limit. If that floor has been climbing year on year and the account rarely, if ever, gets back to zero, the facility is carrying a structural balance rather than genuine short-term swings, and it’s worth treating that portion as capital that needs its own, better-priced facility.
Why do banks review overdraft facilities every year?
An annual review lets the bank check that the facility is still being used as intended and that the business’s financial position still supports it. Persistent utilisation near the limit is one of the clearest signals a bank looks for, and it can lead to a reduced limit or tighter conditions at exactly the point a business can least afford it, which is why it’s worth restructuring the facility before that review, not after.
Is an overdraft or a business loan better for funding growth?
Neither is automatically better, the right answer depends on whether the funding need is temporary or structural. Genuine seasonal swings, like a wage run ahead of an invoice, suit an overdraft. Ongoing growth capital, like a facility that never returns to zero, is usually cheaper and more secure as a term facility. A capital raise assessment can pressure-test which instrument actually fits before the next facility renewal.
Can refinancing an overdraft into a term loan improve cash flow?
Yes, in most cases. Moving the structural portion of an overdraft into a lower-rate term facility with a set repayment schedule frees up interest that was previously funding a permanent balance at a short-term rate, and it restores the overdraft to genuine headroom for real seasonal swings. Folding that view into ongoing cash flow discipline makes it easier to catch the pattern early next time.
How often should an SME in Queensland review its banking facilities?
At least once a year, ideally a few months ahead of the bank’s own annual review, and again after any significant change in trading, such as a new season of growth or a large seasonal order. Many Queensland and NSW businesses only look properly at facility structure when a fractional CFO starts asking why the overdraft never returns to zero, by which point a year or two of avoidable interest has usually already been paid.
Leave a Reply