
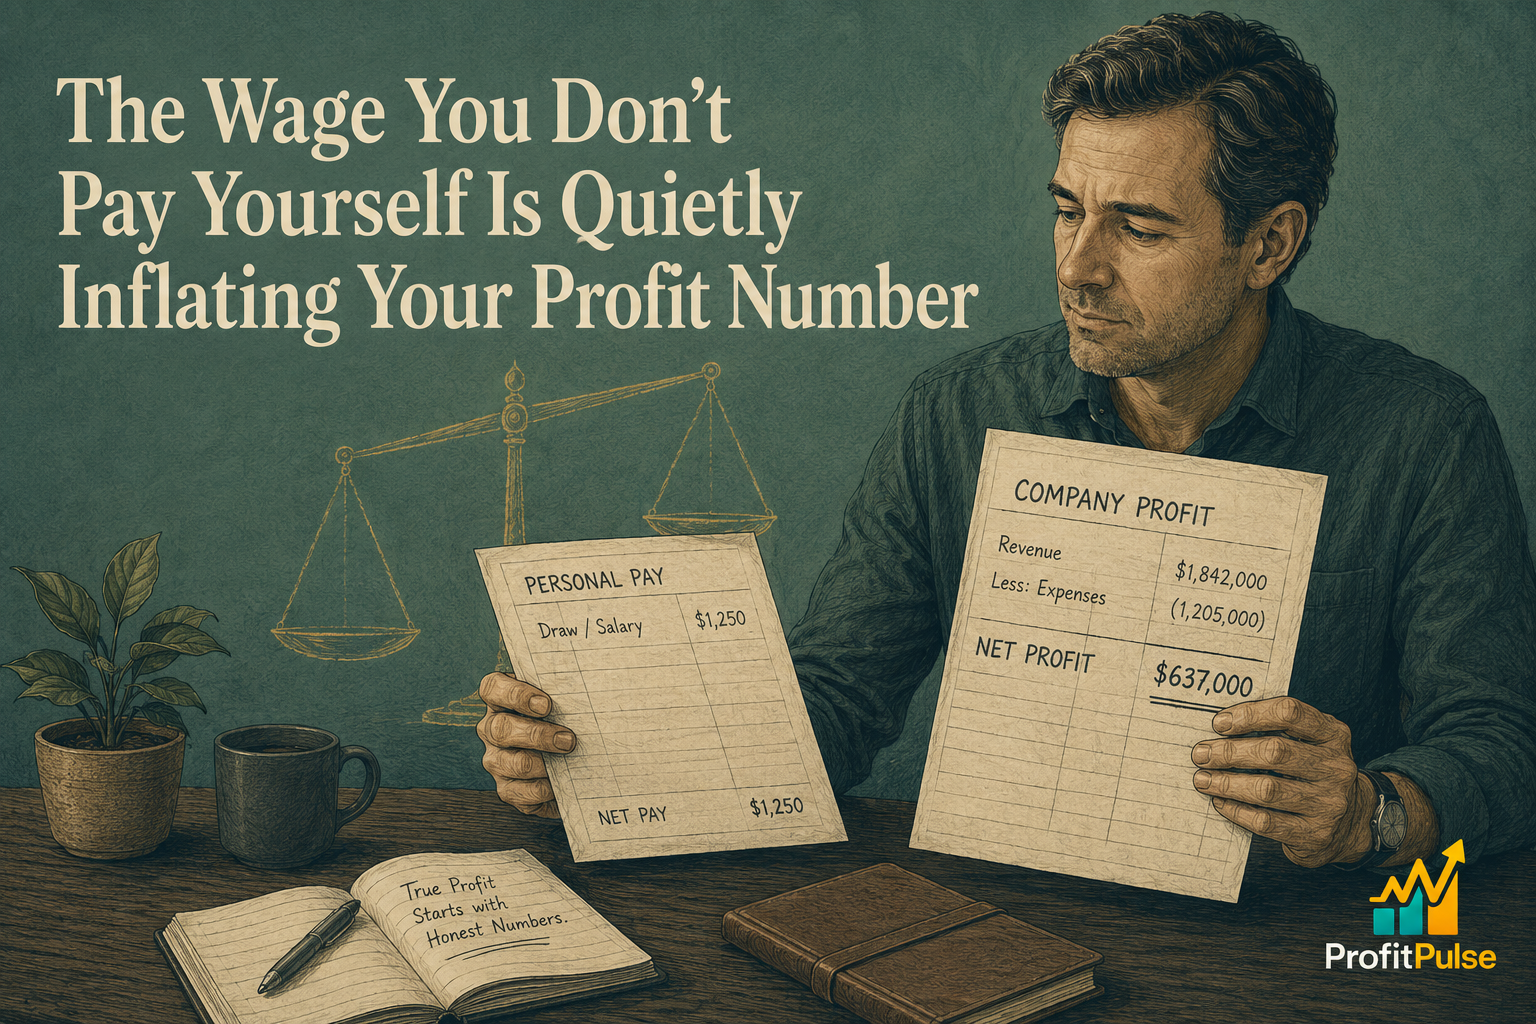
Most owner-led businesses on the East Coast carry a profit line that looks respectable at year end. Pull it apart, though, and a good part of that number is not really profit. It is the gap between what the owner draws out of the business and what it would genuinely cost to hire someone else to do the job the owner is doing, whether that is sales, operations, delivery or all three at once.
This is not a compliance question and nobody is doing anything wrong. Most owners set their own pay based on what the business can spare in a given month, not on what the role is worth in the market. Over a few years that habit becomes invisible. The P&L keeps reporting a healthy margin, and the fact that a chunk of it is unpaid senior labour never gets a line of its own.
The pattern is worth naming because it quietly shapes decisions well beyond the owner’s own pay packet.
The Number Nobody Line-Items
Ask most owners what their role would cost to replace and the answer usually undershoots. A working director doing the job of a general manager, head of sales and finance controller in one person is, in market terms, three salaries compressed into one modest draw. The business books that gap as profit because there is nowhere else for it to sit. It is not deliberate understatement, it is simply that the chart of accounts has no line called value of the owner’s unpaid time.
The effect grows with tenure. In year one, the gap between the owner’s draw and a market wage might be small, because the owner is still learning the role. By year five or six, the owner is usually doing the job better than a hired replacement would, and the gap between what they draw and what that skill is worth has widened, not narrowed. The margin looks stronger with every passing year partly because the discount is compounding quietly underneath it.
Why the Distortion Compounds at the Big Decisions
The trouble starts when this understated cost base becomes the reference point for decisions that assume it will always be there. A pricing review that benchmarks margin against a P&L with a discounted owner wage will land on a price that only works while the owner keeps discounting themselves. A hiring case for a second salesperson, built on the current margin, can look stronger than it actually is once you account for what happens to that margin the day someone has to be paid properly to do part of what the owner currently absorbs for free.
The same distortion shows up in growth planning. A second site or a bigger team is often modelled off the existing P&L as the baseline, without adjusting for the fact that the owner cannot personally absorb the same proportion of unpaid senior labour across two locations that they currently absorb across one. The plan can look fully funded on paper and still come up short in year one, not because the growth was the wrong call, but because the starting margin was never quite what it appeared to be.
Building the Real Number Back In
The fix is a straightforward exercise, even if it is an uncomfortable one the first time it is done properly. Take the owner’s actual role, or roles, and price each one at what it would cost to hire a competent person to do it. Add that figure into the cost base as if it were a genuine wage, then see what profit is left. For some businesses the number barely moves. For others, a business that looked like it was running at a healthy double digit margin is closer to break even once the owner’s true labour cost is counted properly.
This is exactly the kind of gap a Profit Pulse Check is built to surface. It takes the last twelve months of financials, normalises for exactly this sort of understatement, and ranks the highest value fixes once the real number is on the table, rather than the one the P&L happens to show by default.
What Changes Once You See It
Once the real margin is visible, the conversation usually shifts from are we profitable to what is this business actually worth without me working sixty hours a week to subsidise it. That is a harder and more useful question, and it is the one that determines whether a price increase is overdue, whether the next hire genuinely pays for itself, and whether the business could be sold or handed over without the buyer discovering the same gap the hard way during due diligence.
It is also the point where a lot of owners start wanting a second set of eyes on the numbers on an ongoing basis, rather than working it out alone once a year. That is broadly what a fractional CFO does day to day, keeping the true cost base honest so decisions are made against the real margin rather than the discounted one. Whether the business is based in Brisbane or running across sites into Melbourne, the exercise is the same: pay the role what it is worth on paper before deciding what the business can afford to do next.
Frequently asked questions
How do I work out what my own role is actually worth in my business?
Break your week into the functions you cover, such as sales, operations or finance, and price each one at market rate for a competent hire in that function. Add the total as a genuine wage line in your P&L rather than your current draw. A Profit Pulse Check does this exercise properly and shows what margin remains once the real cost is counted.
Why does my profit look healthy but cash still feels tight every month?
Profit and cash move on different timelines, and an understated owner wage often masks the real pressure in both. The reported margin can look comfortable while the business is still carrying the gap between what you draw and what your role would cost to replace. Reviewing cash flow discipline alongside a normalised margin usually explains the gap.
Should I pay myself a market salary or keep taking irregular distributions?
There is no single right answer, and structure often depends on tax and entity advice from your accountant. What matters commercially is that you know what the market rate for your role would be, even if you do not draw it in full, so every pricing and hiring decision is measured against the real cost base rather than a discounted one.
What does a fractional CFO actually do differently to my bookkeeper on this?
Your bookkeeper is doing exactly what they should be doing, which is keeping the ledger accurate for compliance and reporting. A fractional CFO sits above that layer, normalising numbers like an understated owner wage so decisions about pricing, hiring and growth are made against the real margin.
How much of a small business’s reported profit is really unpaid owner labour?
It varies widely by industry and by how many functions the owner personally covers, so we would not put a precise figure on it without reviewing the specific business. What is consistent across owner-led SMEs is that the gap tends to widen with tenure, as the owner becomes better at the role without adjusting what they draw for doing it.
Does this issue matter more for businesses planning to sell in the next few years?
Yes, because a buyer will normalise your owner’s wage during due diligence whether you have already done it or not. Understanding the gap now, well before a sale process starts, means there are no surprises in a valuation and time to close it if the true margin is thinner than the reported one suggests.
Is the owner wage gap different for businesses in Queensland versus other states?
The underlying pattern is the same nationally, though local labour market rates shift what a fair market wage looks like for a given role. For an owner-led business in Queensland, benchmarking against Brisbane and South East Queensland pay rates for the equivalent role gives the most realistic starting point.
Leave a Reply