Retentions across your jobs: the register that brings the money back
Eight jobs, four head contractors and $181,750 held back. How a subcontractor tracks every retention to its release date, and what three months of delay costs.
Eight jobs, four head contractors and $181,750 held back. How a subcontractor tracks every retention to its release date, and what three months of delay costs.
Junior rates for 18 and 19 year olds step up from the first full December pay period. We cost one shop roster over Christmas and show when the cash leaves.
A December claim given on the 7th is due before Christmas. One given on the 14th is due in mid-January. What that week costs a builder.
For businesses that stop trading over Christmas, rent, loan repayments, subscriptions and leave payments keep moving regardless. Planning the cash for that gap needs to start in September, not in December.
PAYG instalments are calculated from your last assessed tax return, not this year's trading. When a business speeds up or slows down, that lag turns from paperwork into a real cash flow event.
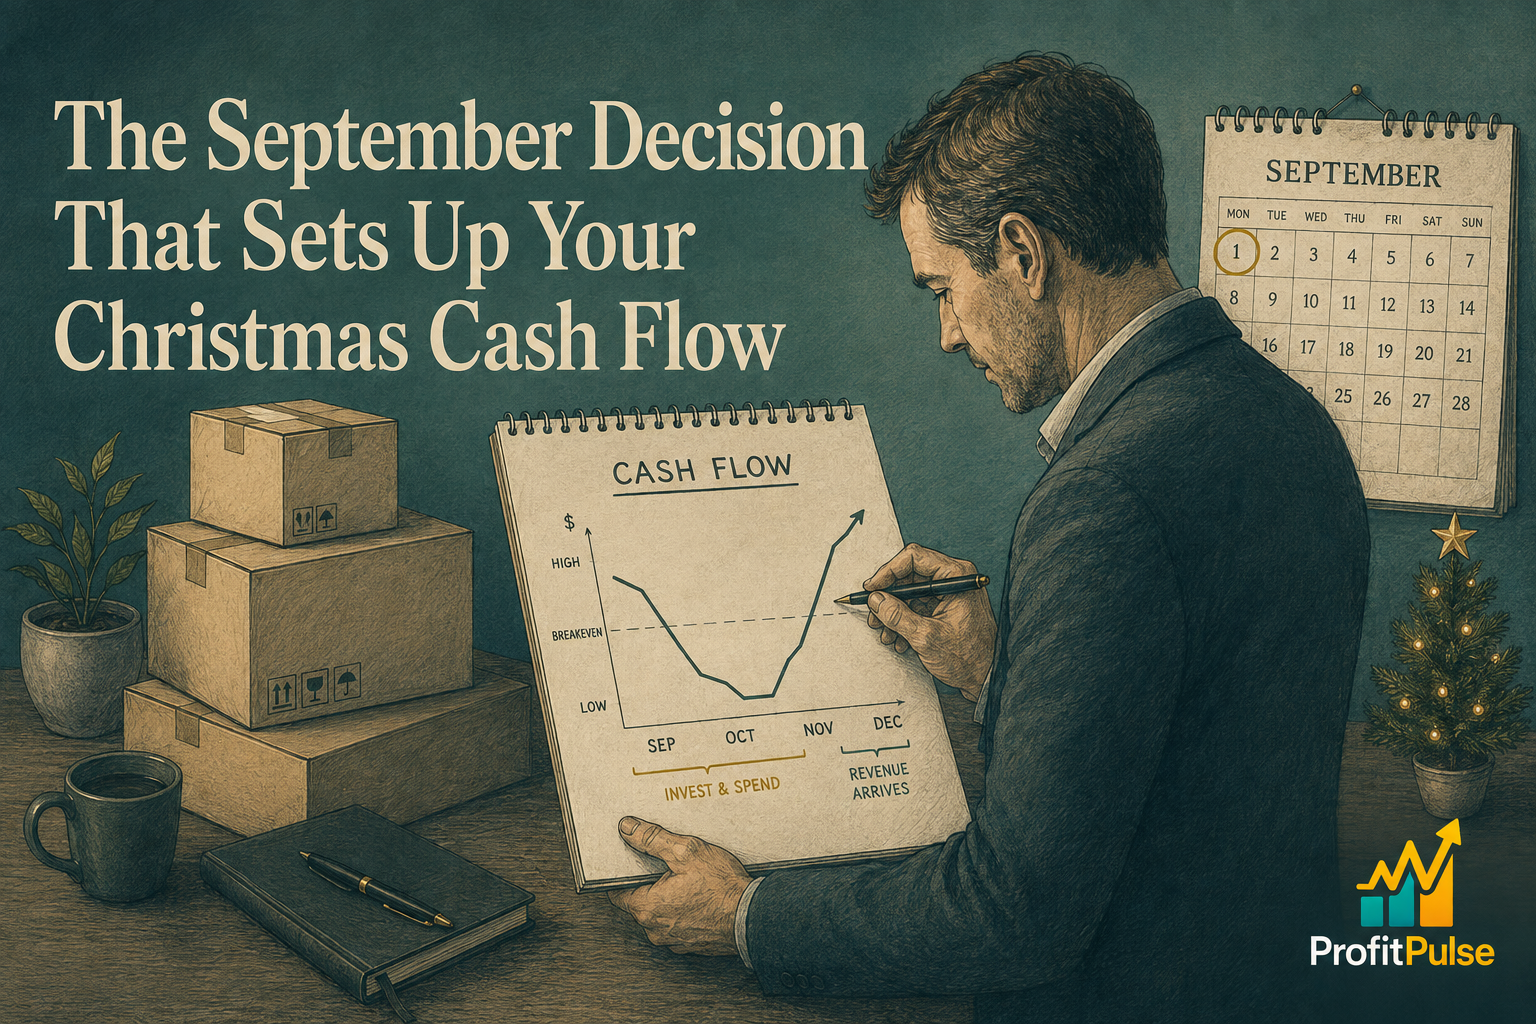
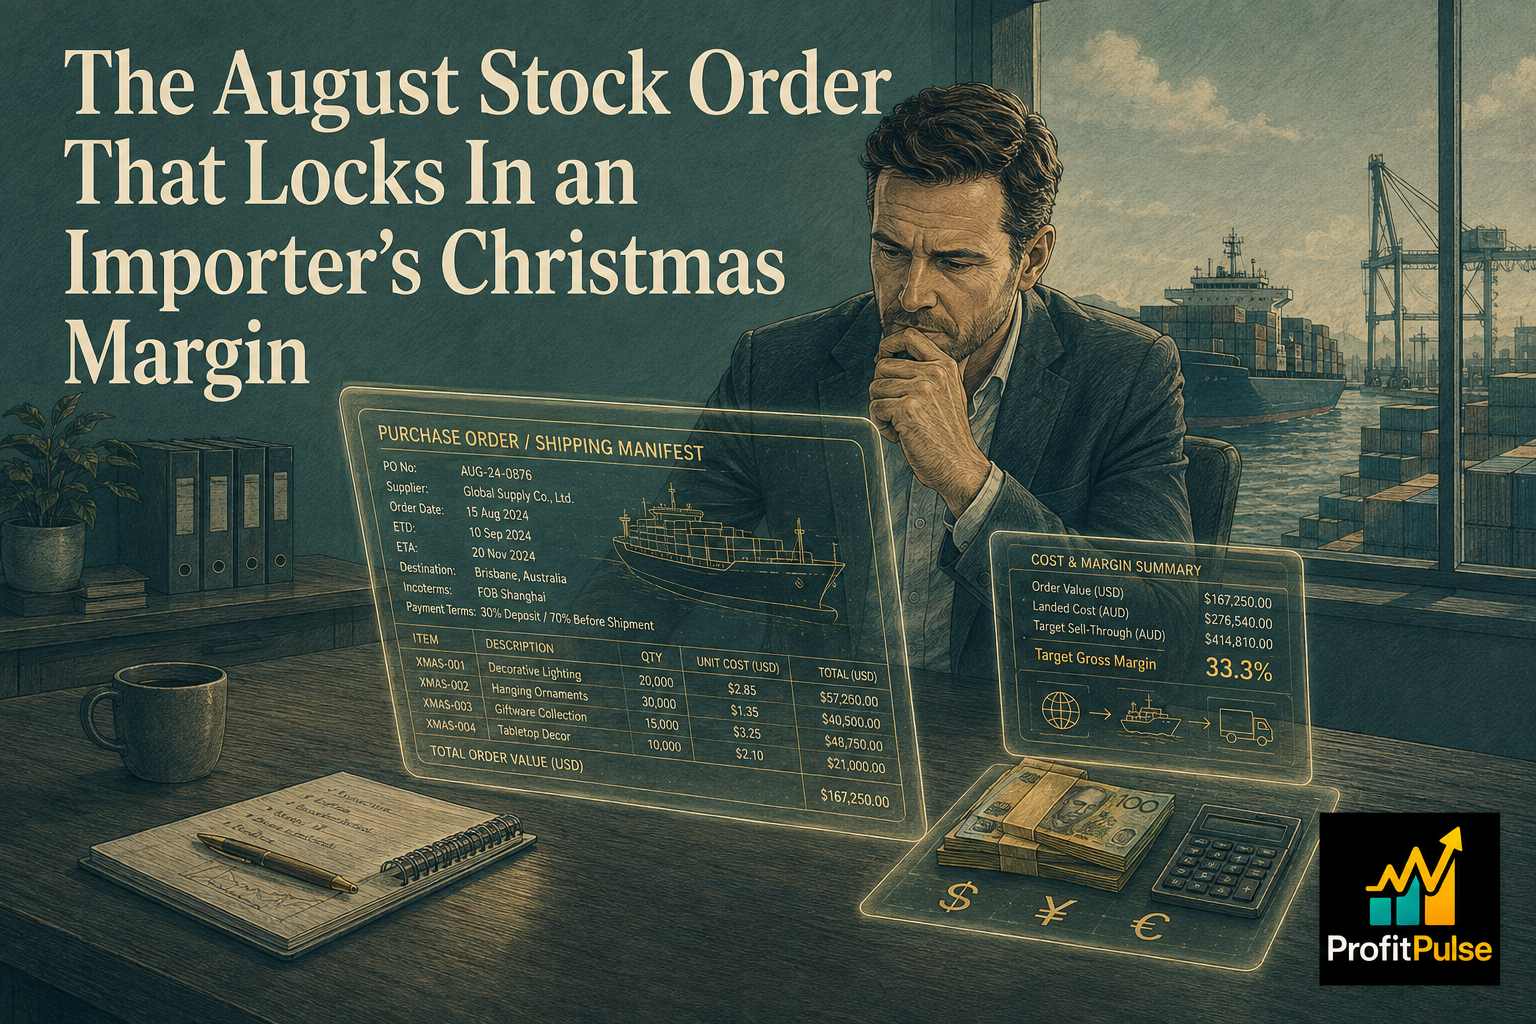
Stock, staffing and marketing spend for the Christmas trading peak goes out the door in September and October, months before the revenue lands. Funding that gap starts now, not in November.
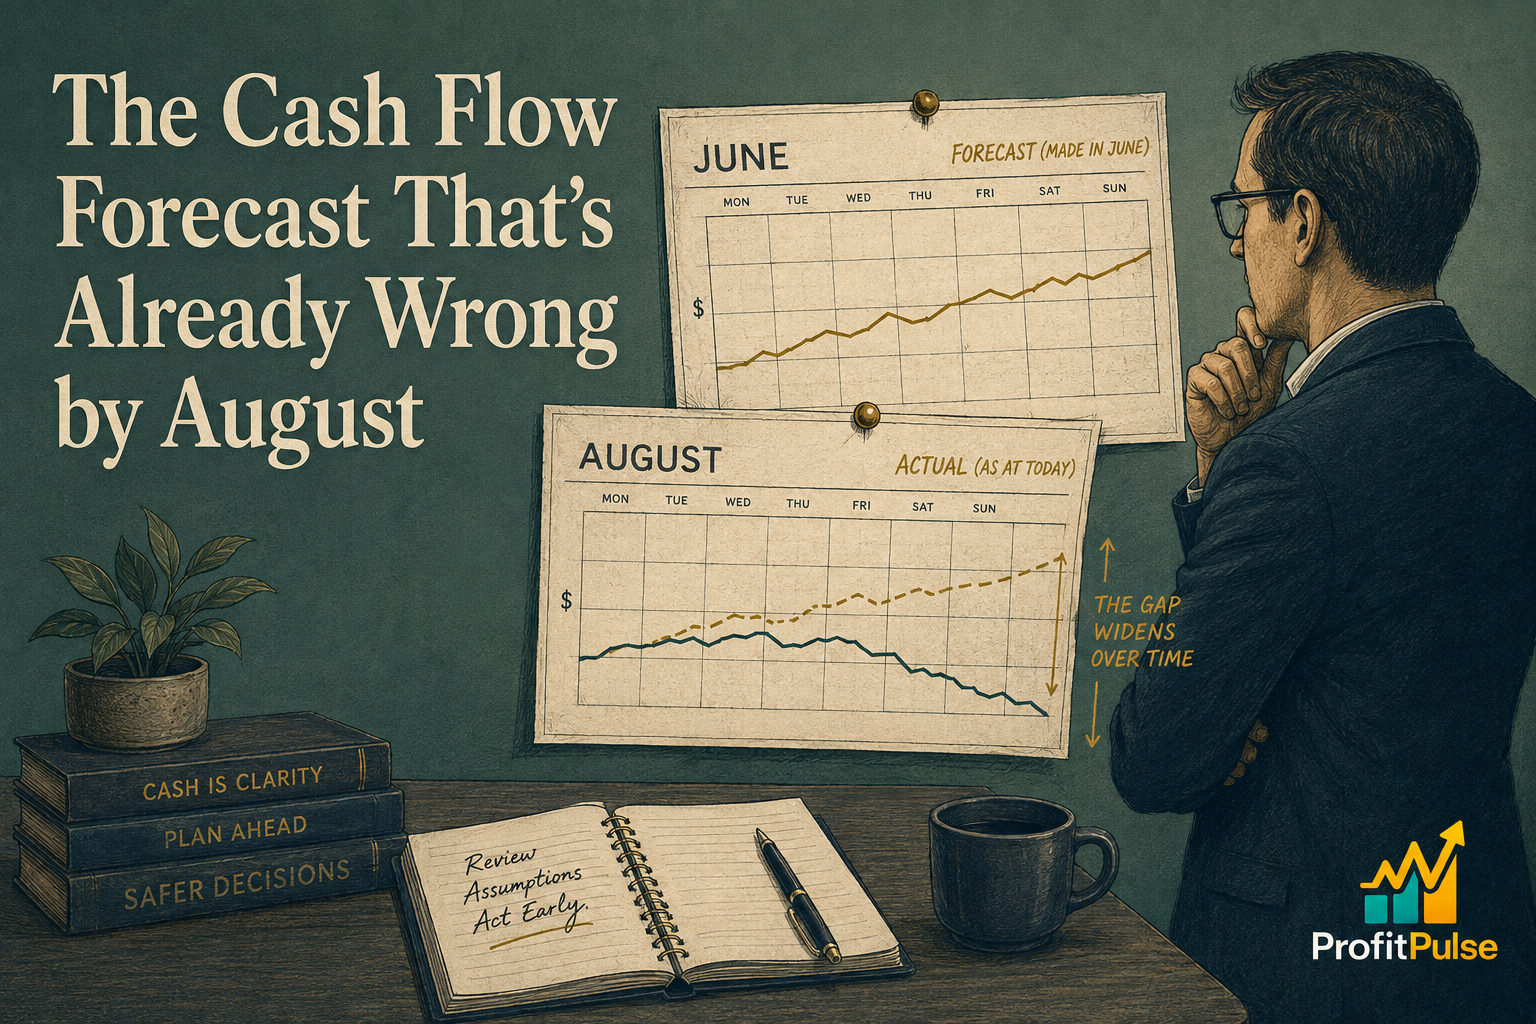
Most owner led businesses build one cash flow forecast a year, usually at EOFY, then stop looking at it. Two months on, the numbers rarely still hold, and that's a discipline gap, not a bad forecast.
Businesses that lodge BAS through a registered agent get until 25 August to pay the April to June quarter. That extra time is not extra cash, and treating it as such is where the surprise starts.
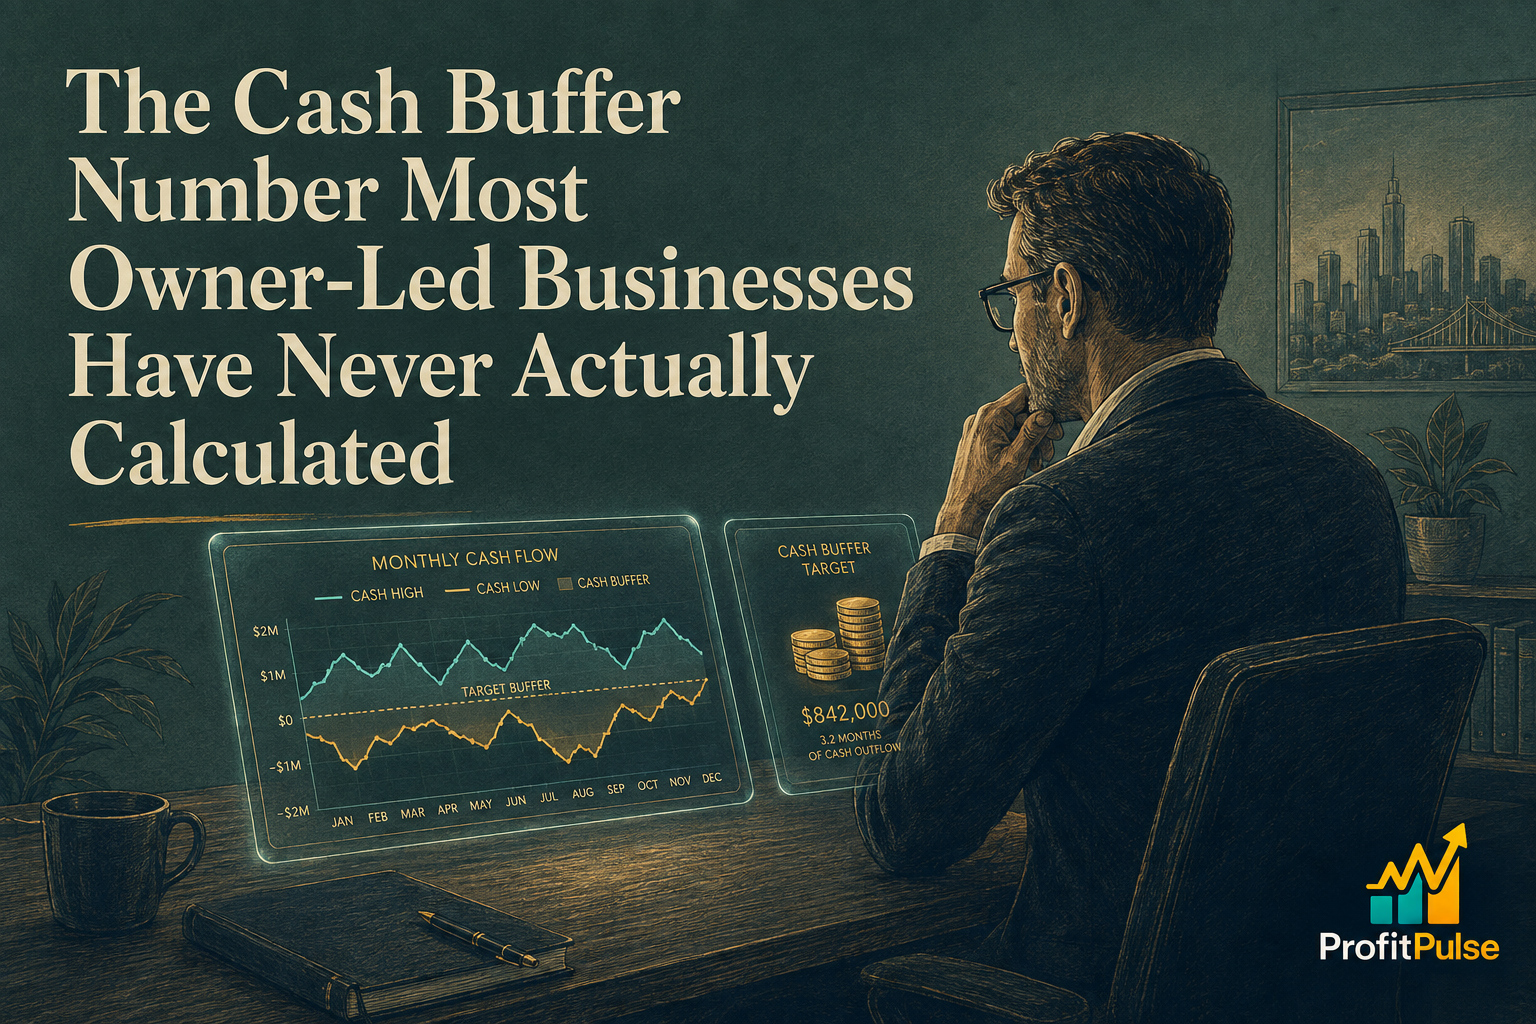
Most owners can name a cash balance that feels safe, but few have ever calculated it. Guessing in either direction has a real cost, and the right number is rarely the generic rule of thumb.
The collections push that tightened cash before 30 June rarely survives August. Here is why debtor days quietly climb again once EOFY urgency fades, and what stops it happening every year.
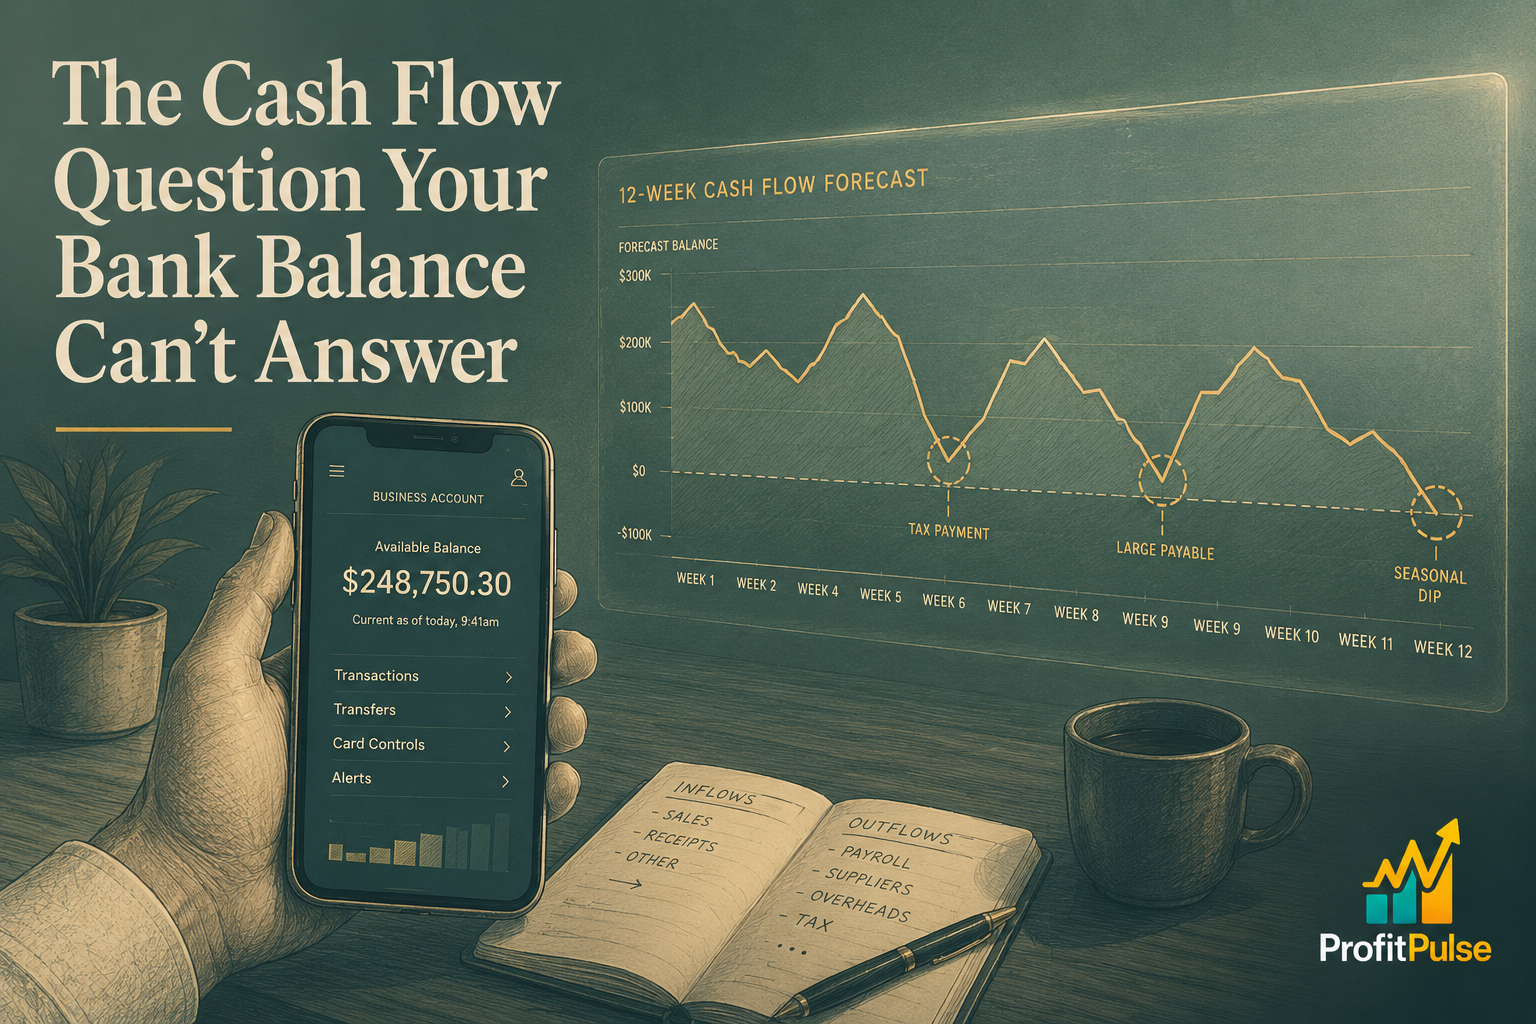
A healthy bank balance feels like reassurance, but it only shows one moment in time. It says nothing about the BAS, super or supplier payments already due to land in the weeks after you checked it.
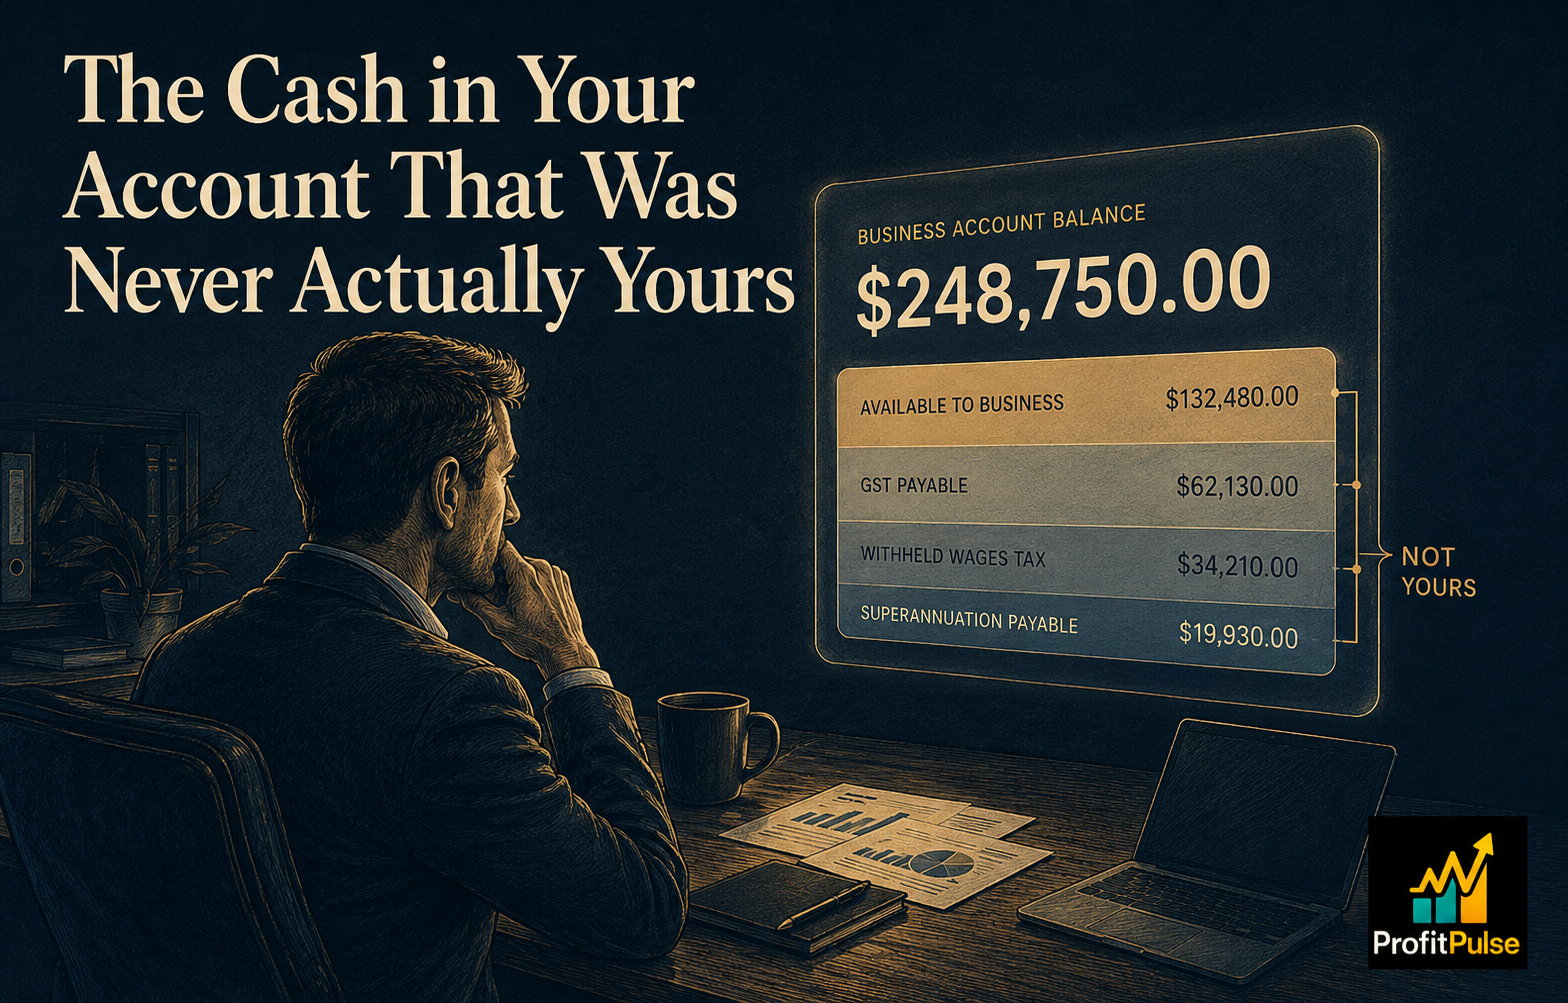
Every business collects GST on sales and withholds tax and super from wages before it is remitted. Until it leaves the account, that money sits there looking exactly like available cash.
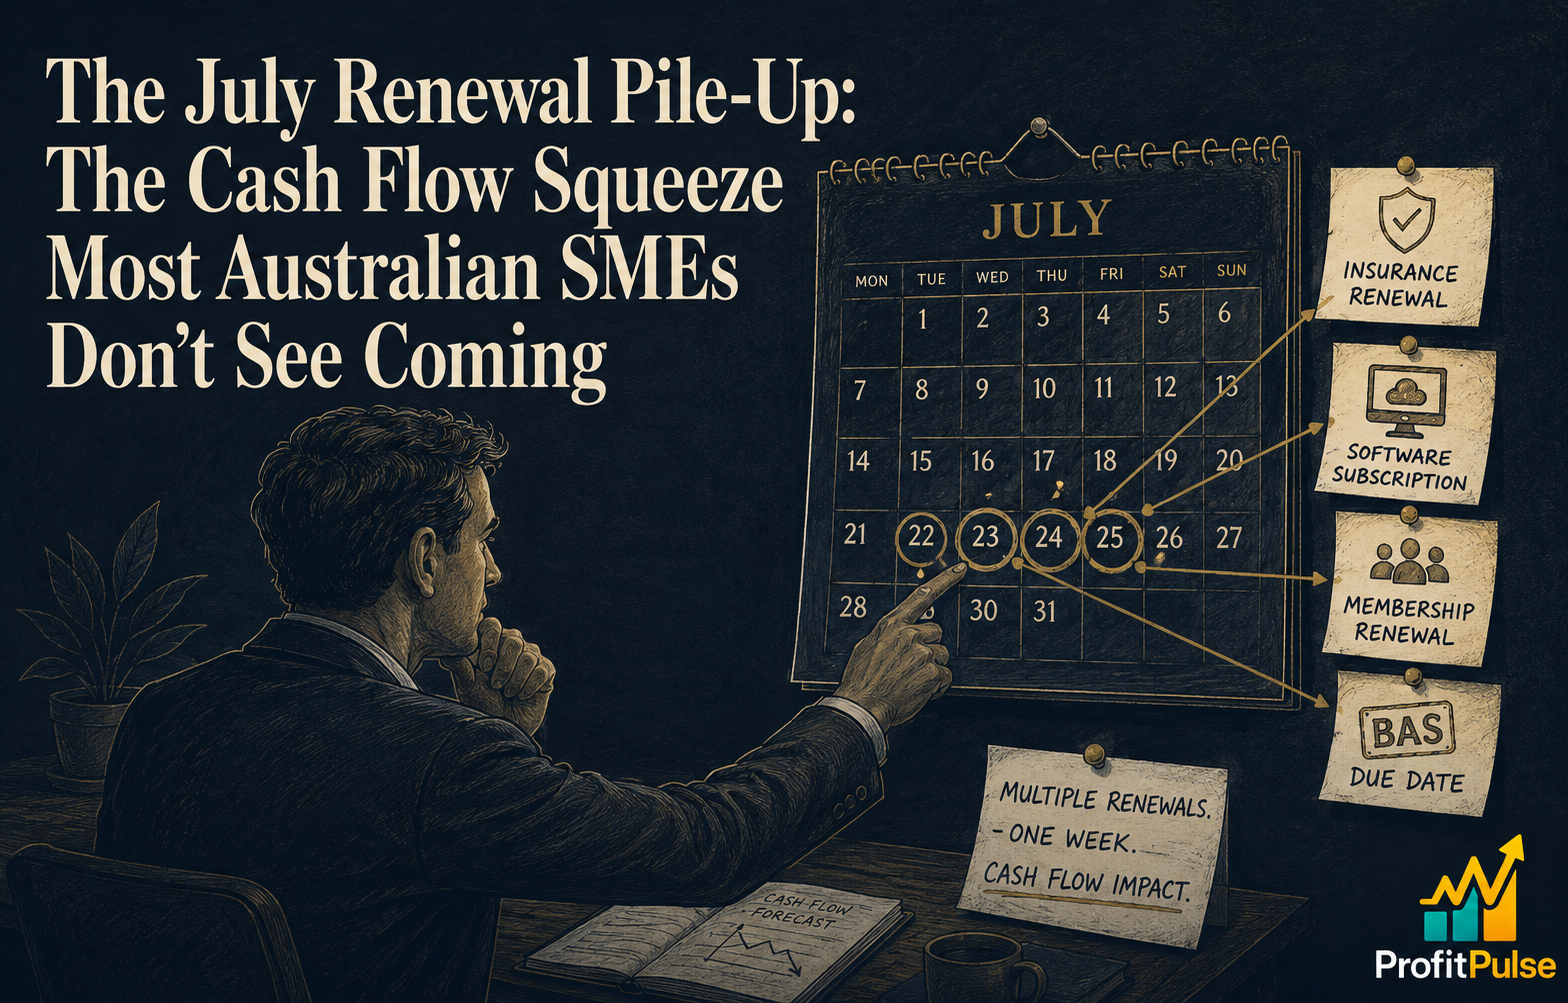
Insurance, subscriptions, memberships and the June BAS payment all reset around 1 July. Individually manageable, together they create a cash squeeze most owner led businesses never see coming.
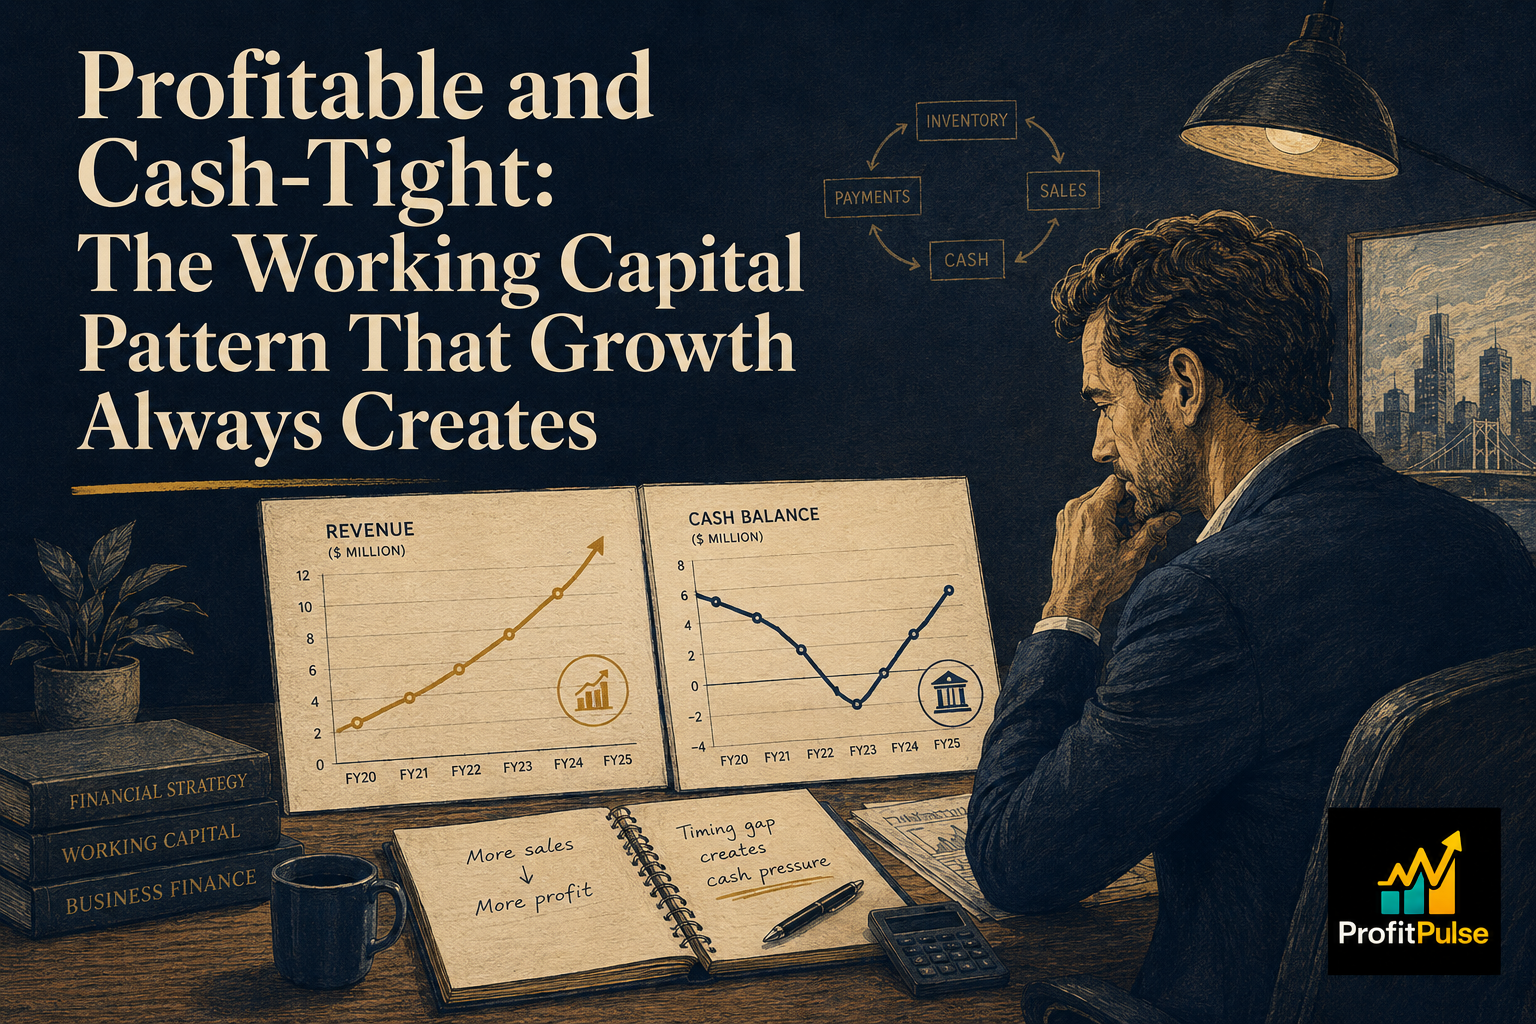
A growing, profitable business often has a tighter bank account than its owners expect. The reason is mechanical: revenue growth requires working capital upfront, before the cash arrives.
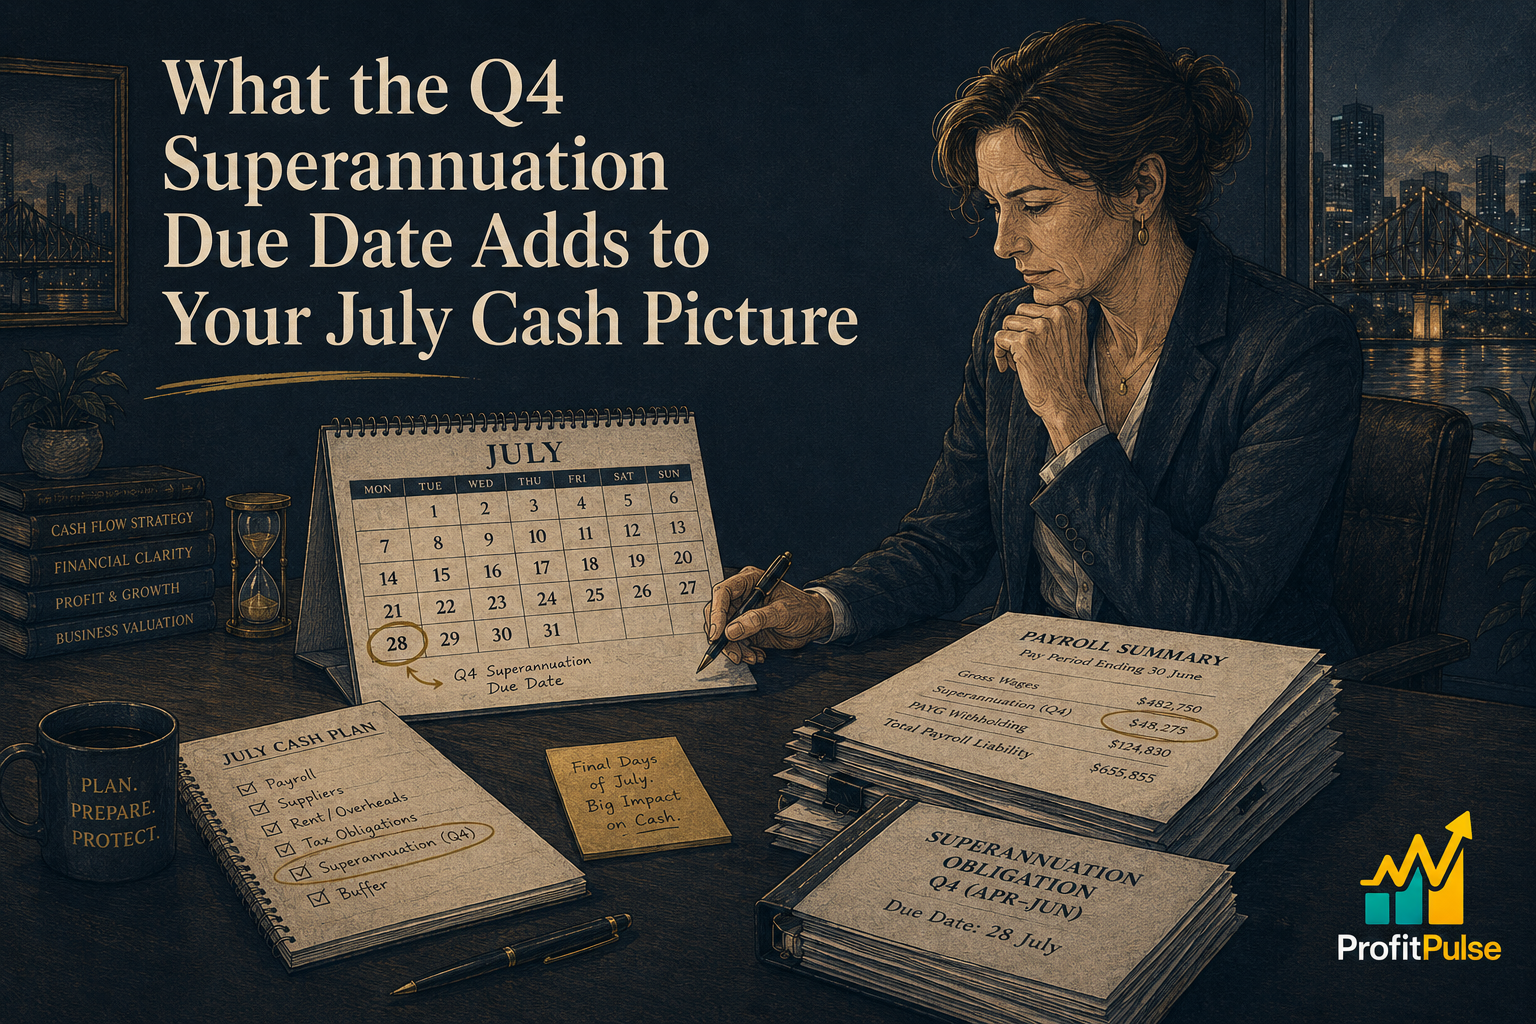
Most businesses plan their June 30 cash position carefully. Fewer have calculated what the Q4 superannuation guarantee adds to their July obligations before the payment date arrives on 28 July.
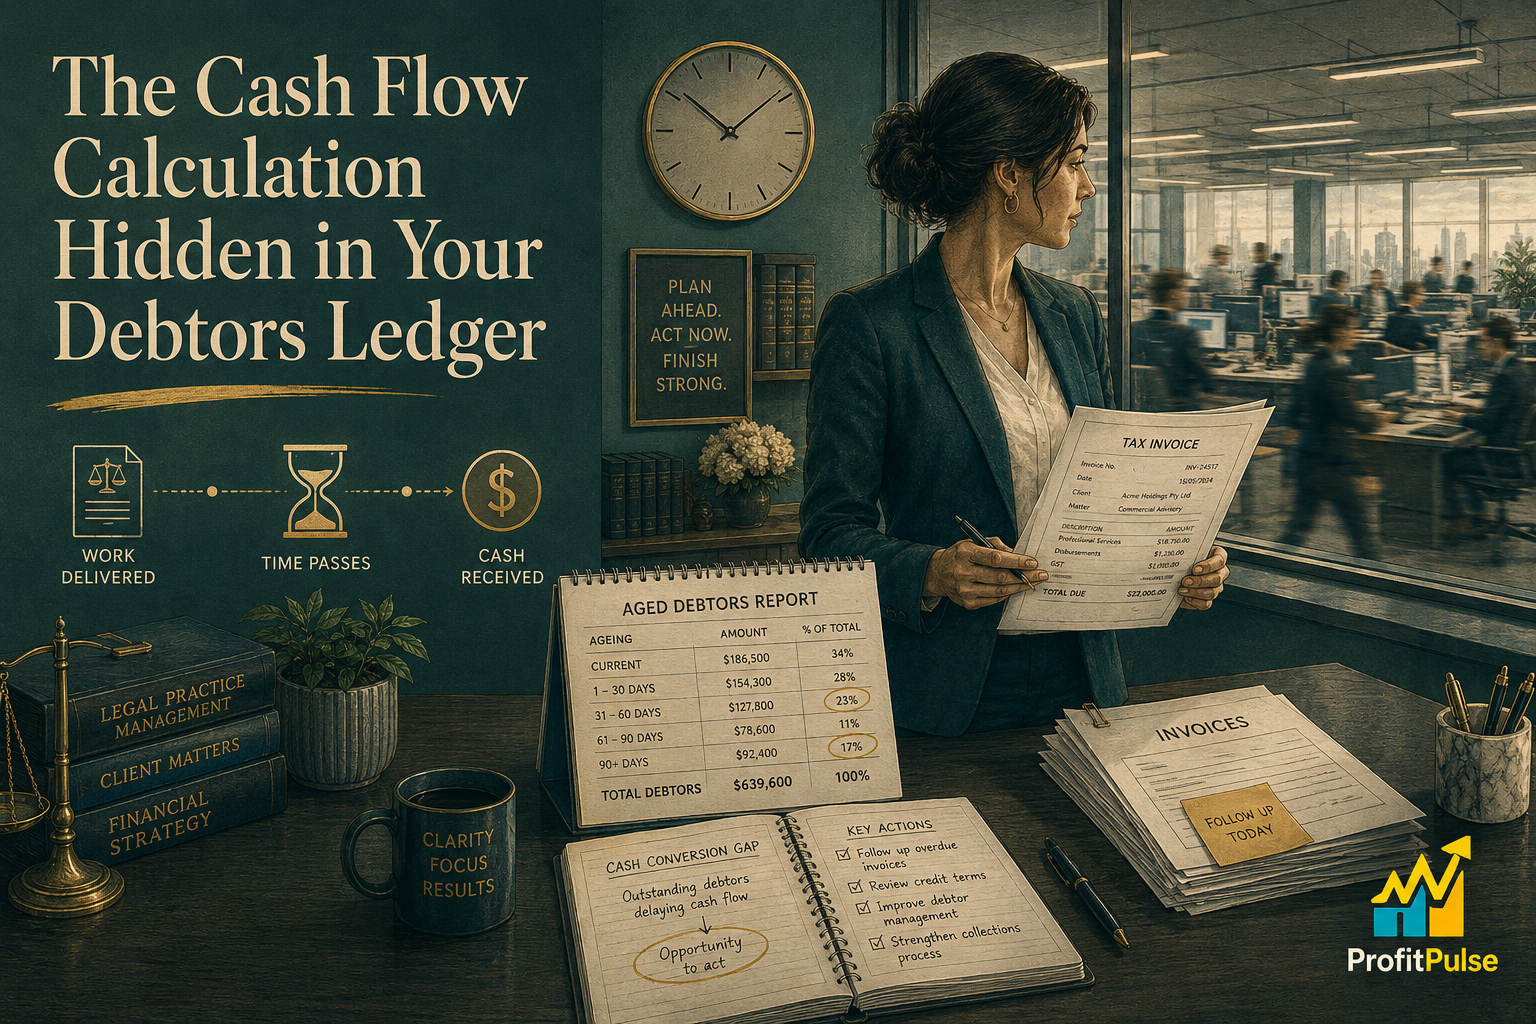
Most business owners know they have outstanding invoices. Fewer have calculated how many days it takes for those invoices to become cash, and what shortening that period would release back into their account.
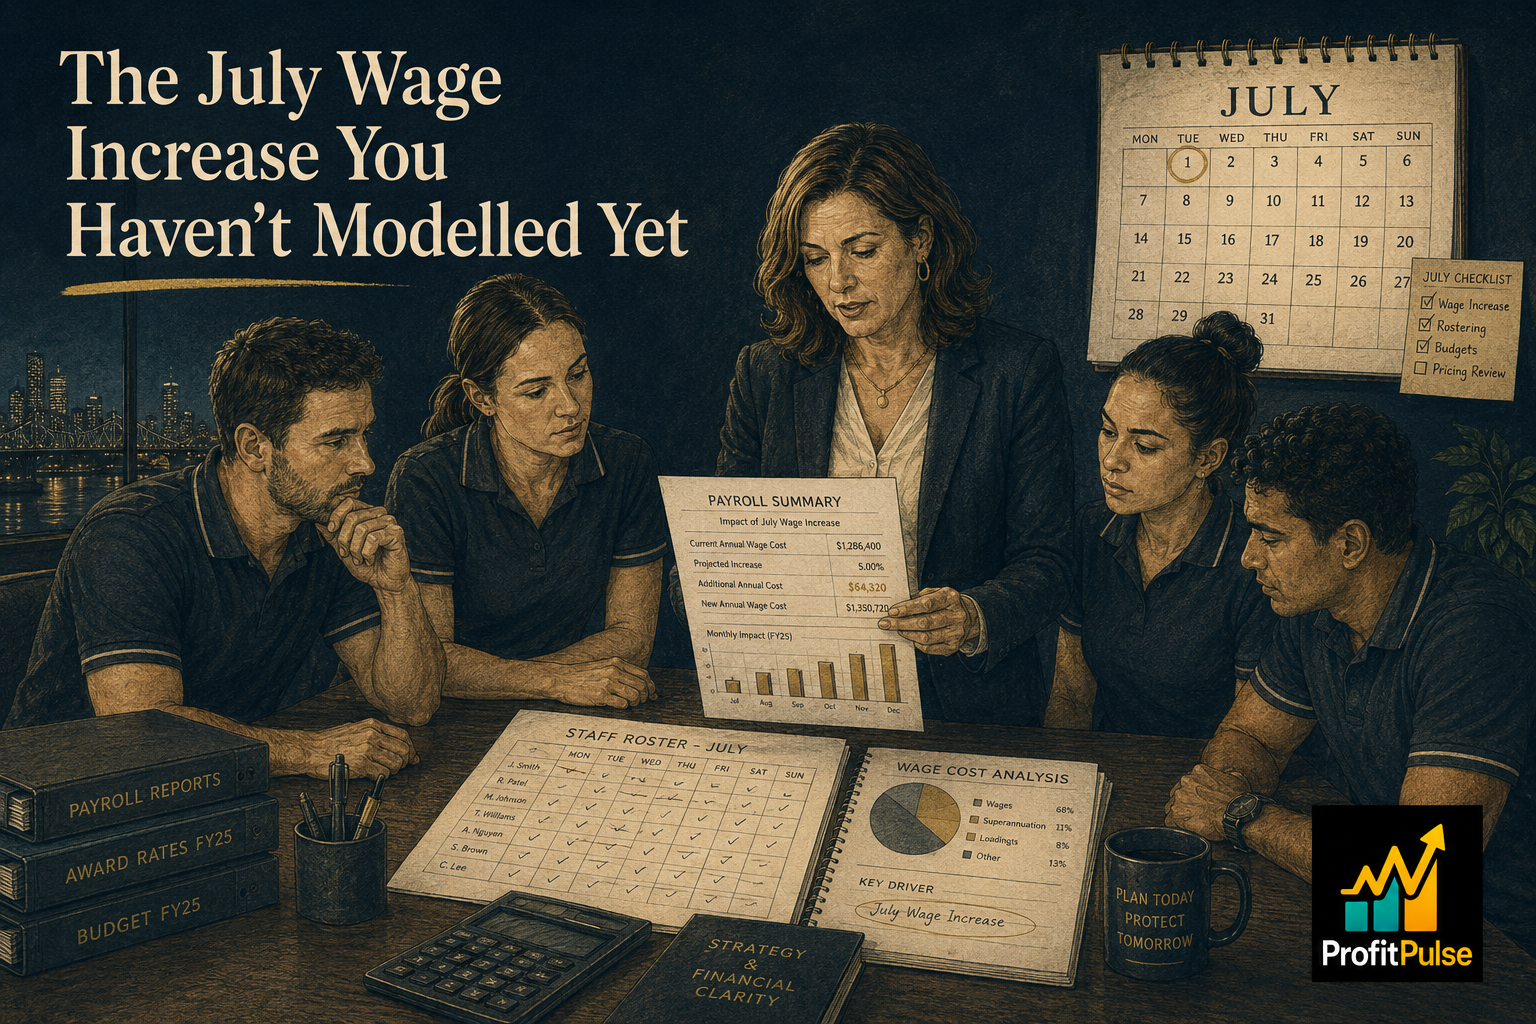
Every July, award wages increase from the first full pay period. Most Australian SME owners know it's coming. Far fewer have calculated what it actually means for their July and August cash position before it arrives.
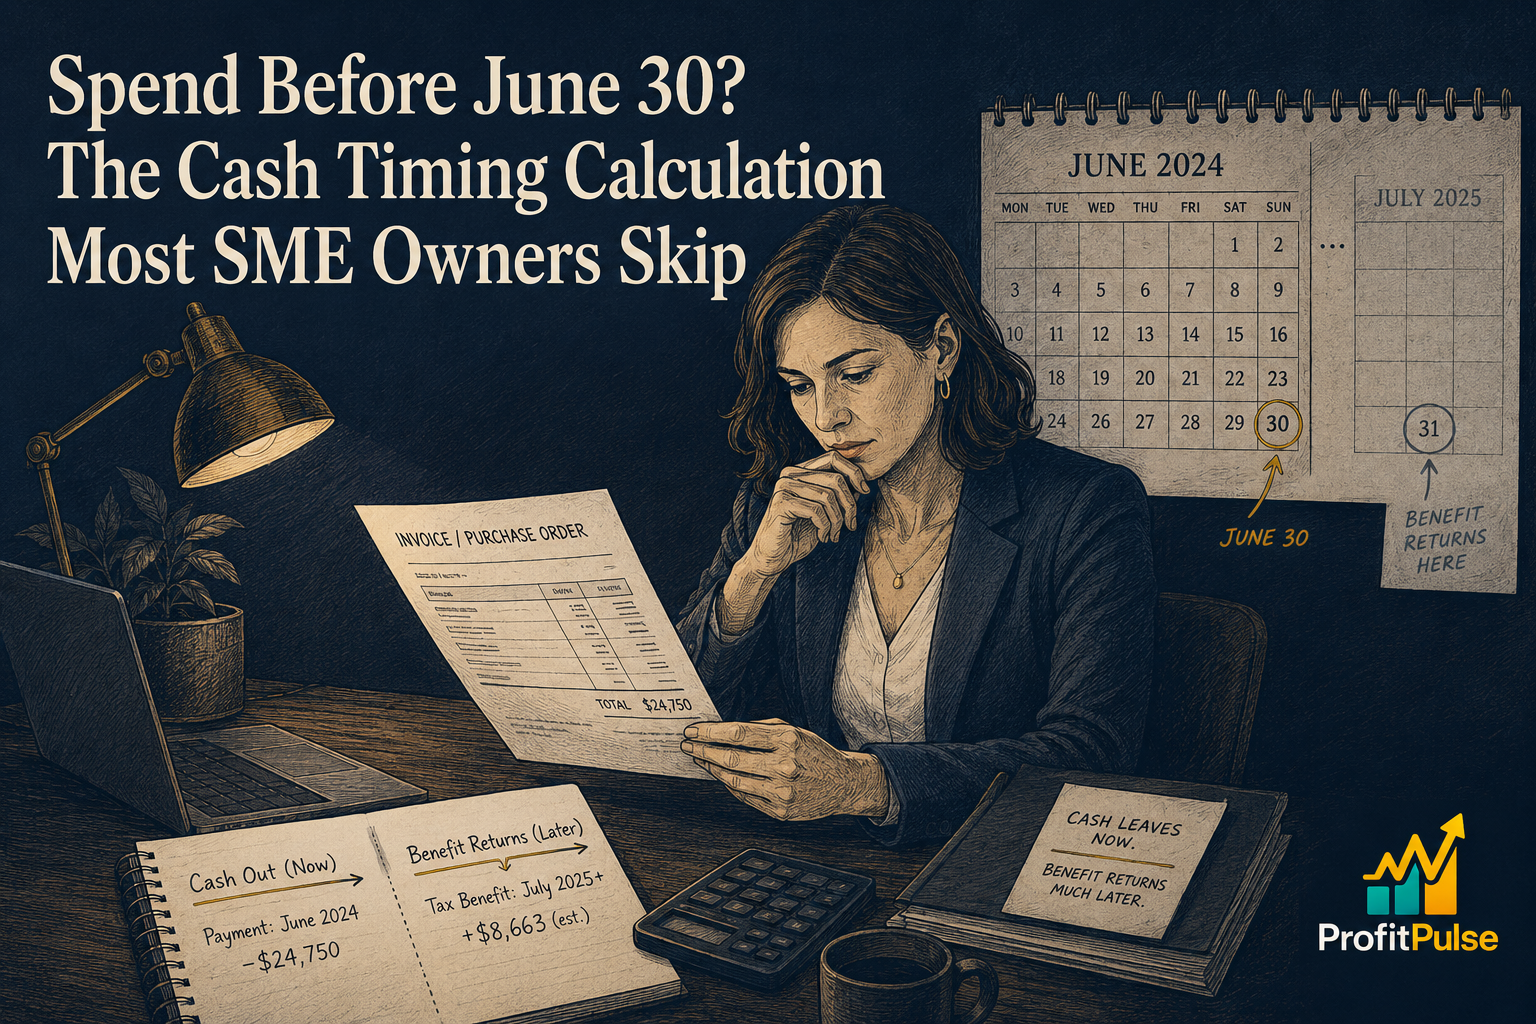
The June push to buy equipment and clear expenses before EOFY makes sense on paper. But cash leaves now, the tax benefit arrives months later, and July can be brutal if the timing has not been planned.
The last weeks of the financial year force timing choices on payments and collections that shape both the result and the July cash position. Here is how to weigh them without straining the bank.
EOFY brings a predictable cash squeeze from tax, supplier runs and year-end spending. Modelling it in early May beats reacting in late June. Here is how to plan your June cash now.
Rapid growth consumes cash through stock, wages and receivables before the new revenue lands. Profitable businesses still run out of money. How to fund growth deliberately rather than be surprised by it.
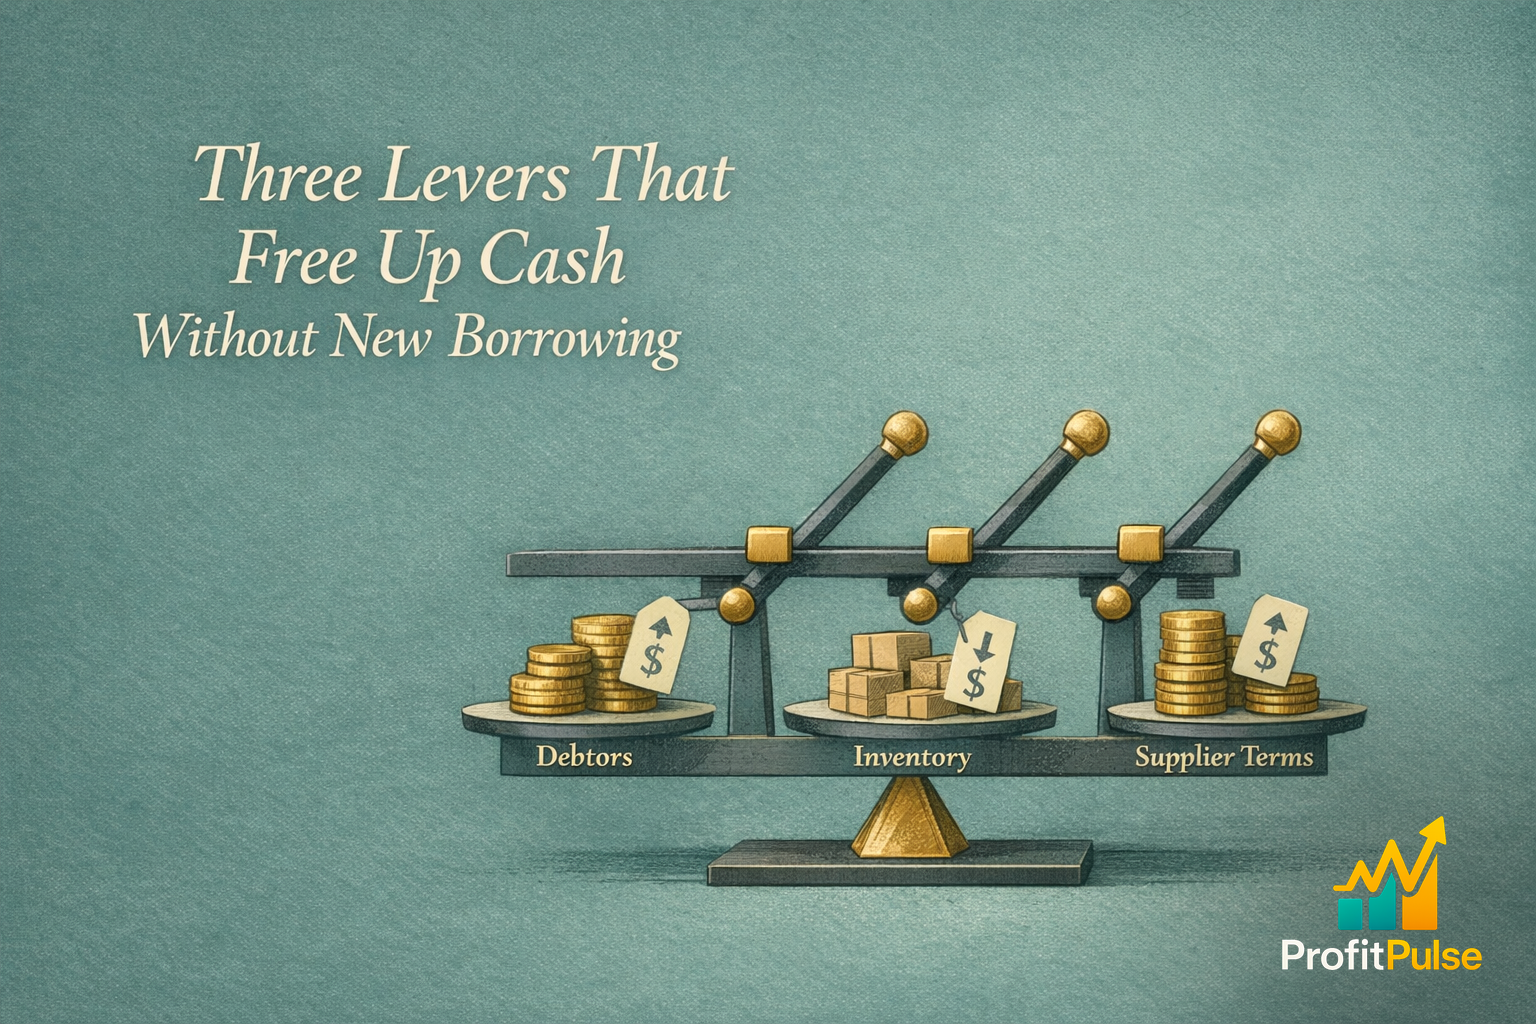
Most businesses are sitting on cash they could release from debtors, inventory and supplier terms before ever approaching the bank. Three working capital levers to pull first, and how much each frees.
A forward cash view before quarter-end lets owners act while there is still time, rather than discovering a shortfall after the books close and options have narrowed.
Work in progress is cash you have already spent but not yet recovered. Slow billing is a silent drain many owners never quantify. The fix is shortening the gap.
Supplier and customer payment terms are a cash decision owners rarely revisit. Small shifts in both directions free up real working capital. Here is how to map the cash cycle and tighten it without strain.